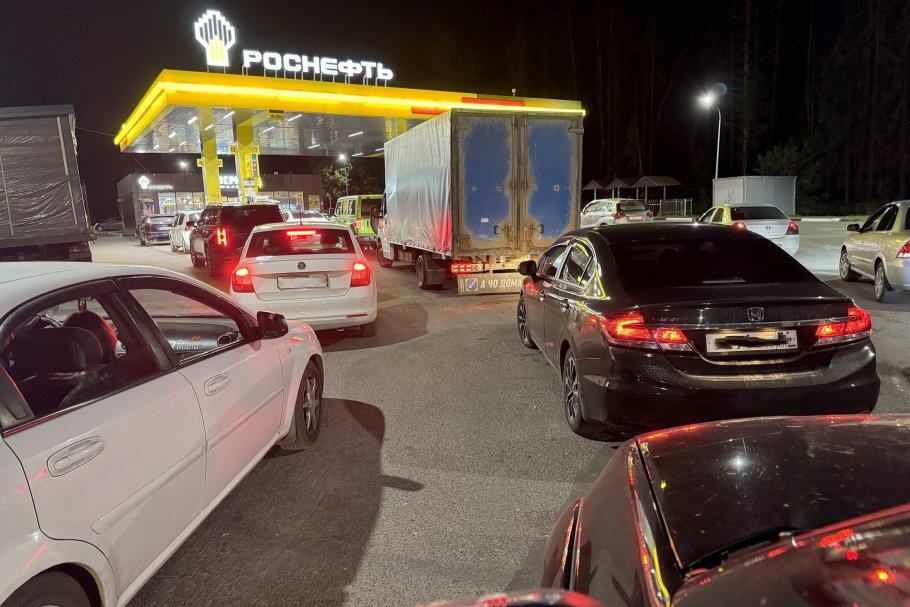
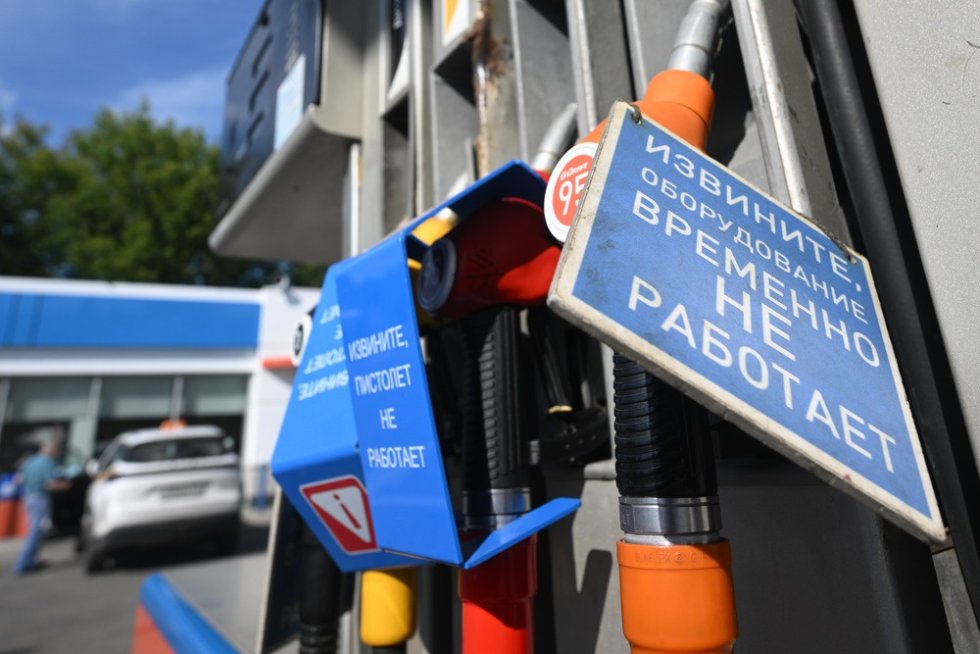
Additionally, in August alone, marine imports of petroleum products into Russia from foreign countries exceeded 300 thousand tons. It is highly likely that this entire volume, or the overwhelming majority of it, consisted of gasoline. This was the product in short supply at gas stations (GS), where long queues formed. Approximately 160 thousand tons were delivered to Murmansk, with the remainder going to Baltic ports. Supplies were sourced from India, Morocco, and Turkey. There were also media reports about the delivery of Egyptian fuel to Arkhangelsk and gasoline from South Korea to Vladivostok.
The main issue with imported gasoline in Russia is its price. All the aforementioned exporting countries are also importers of crude oil. It is even possible that the gasoline they exported to us was produced from Russian oil. As explained in an interview with "RG" by Victoria Trifonova, a senior analyst at the analytical center "Yakob and Partners," imported fuel encompasses not only the cost of gasoline itself but also sea freight, insurance, transshipment, and subsequent transportation within Russia. An additional factor remains the infrastructural constraints associated with the acceptance, transshipment, and pouring of petroleum products in Russian ports. For suppliers, selling such gasoline on the exchange means either setting a significantly higher price or selling it with inadequate margins.
Indeed, in August, when exchange trading of gasoline from foreign countries was taking place, it was sold at a price of 105 thousand rubles per ton, which was 39% higher than the then-current exchange quotations for AI-92 (75,530 rubles per ton). Currently, the quotations stand at 69,819 rubles per ton, but imported gasoline is hardly any cheaper.
Nevertheless, the lack of exchange transactions at present and the fact that only just over a thousand tons were processed in August does not mean that Indian or Moroccan gasoline is not being sold. For instance, in August, Russia imported 188 thousand tons of Belarusian gasoline (with shipments coming via rail and road), of which only 26 thousand tons passed through the exchange.
The majority of marine-imported fuel is sold through direct contracts, bypassing the exchange, according to Sergey Frolov, managing partner at NEFT Research. Direct supplies are noticeably increasing: in August, the "First Murmansk Terminal" sent about 10 thousand tons of fuel (directly) to the domestic market, while for the incomplete month of September, over 20.4 thousand tons have already been dispatched. Thus, fuel is being distributed to gas stations – including major oil companies – directly, without public trading, he emphasizes.
The absence of imported gasoline on the exchange does not mean it is unavailable in Russia, confirms Dmitry Gusev, deputy chairman of the Supervisory Board of the "Reliable Partner" Association and member of the Expert Council of the "Gas Stations of Russia" competition. The role of exchange trading in Russia has significantly declined, with mandatory sales norms for gasoline through the exchange for large oil companies reduced from 15% to 10%, and there is now a priority on direct contracts between suppliers and buyers. The exchange now serves merely as a pricing benchmark; it does not reflect the actual market state, and its role in price formation is minimal.
There are downsides to this situation. As Trifonova notes, the more fuel is distributed through direct contracts, the lower the role of the exchange as a public pricing indicator, making access to fuel supplies more difficult for independent gas stations (over half in Russia) not owned by large oil companies. This is particularly challenging for small networks without developed logistics systems. A balance is crucial for the market: the ability to swiftly redistribute a scarce resource through direct contracts on one hand and maintaining sufficient transparency and competition on the other, the expert asserts.
Meanwhile, the government is discussing measures to increase the attractiveness of imported fuel for our market. A dampening mechanism has already been applied to such supplies. This subsidy from the budget compensates importers for part of the difference between the indicative wholesale prices (established by the government for one year) in Russia and the cost of fuel in external markets. Transportation costs are also considered, but so far only to the Russian port.
The main supplier of gasoline to Russia from abroad is BelarusRecently, Deputy Finance Minister Alexey Sazanov stated that the Ministry of Finance is ready to consider a proposal from the Ministry of Energy to include the transportation costs of fuel from Russian ports to consumption regions in the dampening calculation.
Trifonova believes that accounting for the transportation costs of imported fuel within Russia could significantly improve the economics of such supplies. However, this measure alone will not bring imported fuel back to the exchange.
Frolov notes that discussions are also underway to extend the zero rate of import tariffs on gasoline until mid-2027 (currently in effect until the end of 2026). However, the Ministry of Finance does not support the consideration of the foreign premium (the difference between the purchase price and the exchange indicative) as it believes that its value cannot be reliably determined. Thus, the approach is to compensate for logistics within the country – yes; to compensate for the foreign purchase price – no, the expert emphasizes.
The question remains as to how critical marine supplies of imported fuel are for us now. According to Sergey Tereshkin, CEO of Open Oil Market, it can be confidently said that supplies from India or Turkey do not play a significant role at this time. This is their key difference from supplies from Belarus. The share of Belarusian supplies in gasoline consumption in Russia has increased from 2% to 6%. In some regions, this figure may be even higher. Building infrastructure for supplies from distant foreign countries is a challenging task, especially now, when global oil processing is at multi-year lows and the underloading of Middle Eastern refineries has already become one of the reasons for the shortage in the global fuel market.
Source: RG.RU