The number of fuel stations (FS) for sale in Russia is increasing. This pertains not only to single independent fuel stations not owned by major oil companies, but also to networks that are "offloading ballast"—disposing of their least profitable assets.
The number of ads for the sale of fuel stations on various trading platforms and oil company websites has risen 5.5 times over the past five years. However, an ad does not necessarily indicate a sale; rather, it points to the owners’ desire to divest from the business.There are typically two reasons for this decision: the desire to profit from selling a promising business or, conversely, the attempt to shed a loss-making enterprise. In the latter case, if the asset fails to sell, it is highly likely that it will be closed. This, in turn, impacts fuel availability, especially in regions lacking major network filling stations. Furthermore, a reduction in the number of players inevitably leads to decreased competition, which, if not resulting in price increases, will maintain them at a high level.
Fuel stations for sale include not only single outlets but also entire regional networks.The number of FS in our country began to decline as early as 2025. According to "OMT-Consult," this decrease was 1.6%. In the first half of this year, the decline continued with an additional drop of 1%. Much of this reflects the disappearance of mobile FS (container-based).
By the second half of 2026, there were approximately 28,000 fuel stations in Russia, with just over 23,400 of them being classic FS (non-mobile stations selling petrol and diesel).
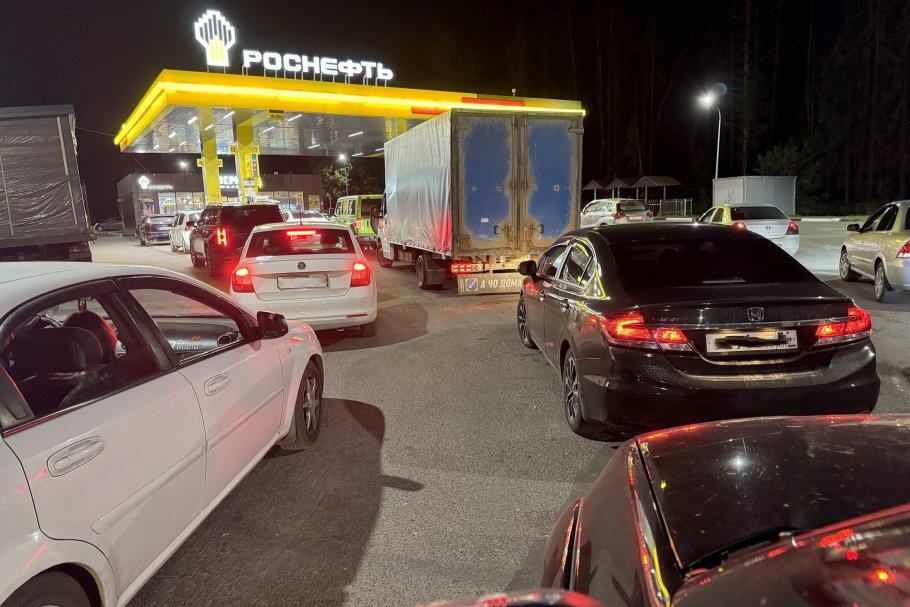
The share of independent players in the total number of FS is around 65%. The majority of these stations are located in the east and south of Russia. However, when it comes to the sales volume of petrol and diesel, independents only account for 30% of the market. Generally, independent FS procure fuel in small wholesale quantities, positioning themselves in the segment where the highest price hikes and supply disruptions were noted this summer. This may explain the owners’ desire to sell their businesses, although the issue also affects larger players.
For instance, last week, operational FS, land plots for business along federal highways, and manufacturing sites of "Bashneft-Retail" were put up for sale or rent. The number of listed assets can be gauged by their geographic distribution, which includes Sverdlovsk, Chelyabinsk, Kurgan, Orenburg, Samara, Ulyanovsk, Penza, Vladimir, Moscow, Ryazan, and Smolensk regions, as well as the republics of Tatarstan, Mordovia, Udmurtia, Chuvashia, and Mari El. Earlier, it was revealed that "Gazprom" and "Lukoil" were selling their "non-core" FS. Lukoil's website still lists eight FS for sale.
Regarding independent players, everyone's aware of the issues faced by one of the largest independent FS networks, "Trassa," which is experiencing a debt crisis and may face external management or be sold off. Currently, about 170 FS are for sale on various trading platforms.
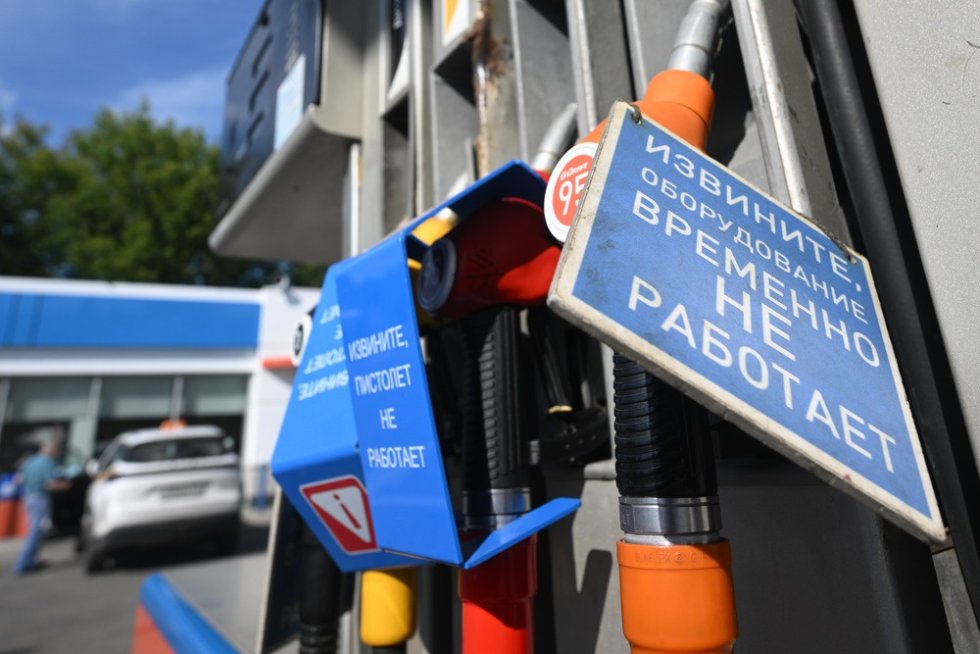
However, as Deputy Chairman of the State Duma Committee on Energy, Yuri Stankevich, noted in a conversation with "RG," it is not entirely appropriate to talk about a "mass sale." Today, the fuel retail sector represents a heterogeneous competitive space, with fragments in different regions of the country varying significantly. The fuel shortage has primarily affected independent FS. These stations have often "pulled hoses," leading to a perception of market saturation, where de facto assets find no application.
Nevertheless, the geography of FS sales ads covers almost the entire country. According to Sergey Tereshkin, General Director of Open Oil Market, the situation is attributable to the decreasing profitability of FS operations and issues with fuel availability for trading. Exchange prices for petrol and diesel have risen by 30-37%, with even higher increases in the small wholesale segment, resulting in fuel retail being in a tougher position than the oil refining sector, which is subsidized.
Additionally, the decreased fuel availability on the exchange is due to reduced mandatory sales quotas for major oil companies. The lower the quota and the more substantial the concessions for over-the-counter transactions, the less fuel is available for traders. Ultimately, independent FS suffer losses as they purchase petrol and diesel from traders. The reduction in the physical volume of sales means that FS operators earn less on each liter of fuel sold.
According to Sergey Frolov, Managing Partner at NEFT Research, the redistribution of ownership in the retail fuel market under current conditions was anticipated. Currently, private owners of single stations or small, inefficient networks are exiting the business. Large oil companies are also optimizing unprofitable points and restructuring their networks to adapt to new conditions.
The expert believes that the reduction in the number of FS is unlikely to seriously impact the overall situation in the fuel sector, as they were often standing empty. With improvements in fuel supply conditions, the number of private FS will likely increase again, especially if high prices persist.
It is hardly possible to sell FS now; this had to be done two years ago when the business was profitable, asserts Dmitry Gusev, Deputy Chairman of the Supervisory Board of the "Reliable Partner" association and a member of the expert council for the "FS of Russia" competition. The issue lies not in the fact that they are being sold, but in our uncertainty about how necessary these stations are. However, the priorities for the domestic fuel market are now defined. The main task is to ensure that the network stations of major companies, agricultural producers, and industrial enterprises are prioritized, rather than independent FS networks, clarifies the expert.
A similar view is expressed by Stankevich. "Unfortunately, the situation in 2026 demonstrated that the retail fuel market has developed chaotically for many years. We do not have a qualified understanding of the sufficient number of FS whose presence would allow us to confidently speak about the availability of infrastructure for consumers. Systematic planning for the development of the retail network is not taking place, which has resulted in many municipalities—even in Central Russia—lacking operational stations. For instance, systematic planning for electricity and heat supply facilities is conducted at the level of documents regularly updated by the government (site placement schemes). The situation in fuel retail also needs to be corrected," he said.
Source: RG.RU