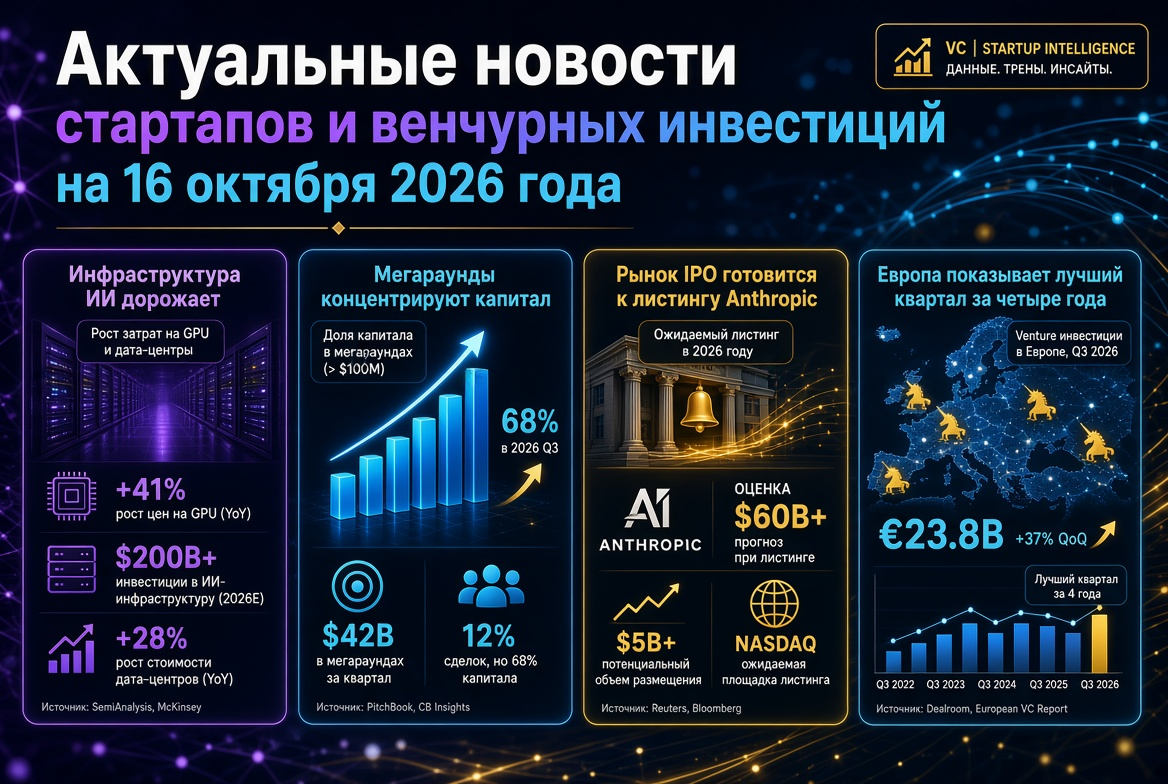
Key Startup and Venture Investment News for October 15, 2026: Q3 Summary, Anthropic IPO Preparations, Mega Rounds in AI, Quantum Technologies, and Defense, Major M&A Deals, and New Venture Funds
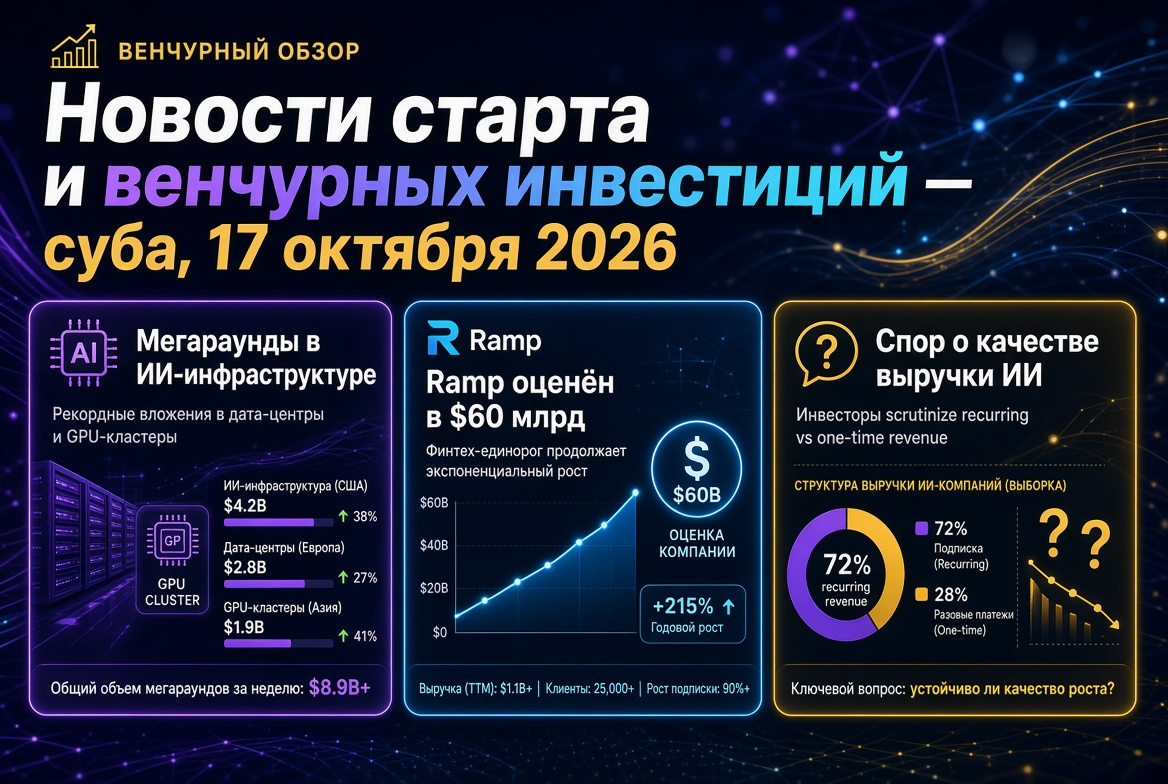
The global venture market approaches mid-October 2026 with conflicting signals. The volume of venture investments over the first nine months has reached a historic record; however, capital is increasingly concentrating within a narrow circle of companies related to artificial intelligence. For venture investors and funds, three themes are coming to the forefront: preparation for the largest IPO of the decade, a record number of rounds exceeding $1 billion, and the activation of M&A deals as a channel for exits.
Key events shaping the startup market agenda this week:
- Anthropic IPO delayed to November — the roadshow is expected to commence during the week of November 9, with a target valuation being discussed around $2 trillion.
- Record mega rounds — 27 startups raised rounds of $1 billion or more in the third quarter.
- Chinese AI accelerates — DeepSeek, Manus, and Infinigence AI closed significant funding rounds.
- M&A at the intersection of quantum technologies and cybersecurity — IonQ acquires Elisity for up to $1.3 billion.
- Record fundraising in the UK — British venture funds raised $6.9 billion in the quarter.
Q3 Summary: Record Nine Months and Capital Concentration Growth
According to Crunchbase, the global volume of venture investments in the third quarter of 2026 reached $159 billion, with nearly 6,000 funded startups. This figure is 25% lower than the record second quarter ($212 billion) but 53% higher than a year ago. Over nine months, the venture market attracted $679 billion — a historic high for the equivalent period.
Key parameters of the quarter:
- $102 billion, or 64% of all venture investments, went to startups in the artificial intelligence sector.
- 27 rounds of $1 billion or more — an absolute record compared to 16 in the second quarter and 14 in the first; these accounted for nearly a third of total capital.
- $91 billion (57%) was raised by American companies, with the San Francisco Bay Area accounting for about a quarter of the global volume.
- Early stage funding grew by 25% year-on-year — reaching $40.6 billion, indicating continued appetite for seed and Series A rounds.
Data from PitchBook and NVCA in the US confirms the trend: from January to September, the volume of venture deals in the country reached $515.8 billion, with 82.7% attributed to AI. Notably, first-time fund managers closed only 81 funds totaling $4.9 billion — new teams in the capital market still face challenges competing with mega funds.
Anthropic IPO: November Window and Valuation Debate
The primary topic for the public market is the preparation for Anthropic's IPO on Nasdaq. According to recent reports, the roadshow has been postponed by about a month and is expected to start during the week of November 9, allowing for a debut before Thanksgiving. The company is anticipated to disclose its financial results for the third quarter prior to the marketing of the offering.
- Last private valuation — approximately $965 billion following the Series H round in May 2026.
- IPO benchmark — investors are discussing a valuation range of $1.8–2 trillion and raising up to $100 billion.
- Skeptics — the independent analytics firm New Constructs has labeled the upcoming offering as overvalued and assessed the business significantly lower than market expectations.
For venture investors, the risk factor is clear: shares of SpaceX, which went public in the summer with a valuation around $1.77 trillion, lost nearly half of their value by the end of July. The outcome of the Anthropic IPO will be a key indicator of whether the public market is willing to pay private market multiples for AI companies.
Mega Rounds in AI: Models, Defense, and Legal Tech
October continues the trend of substantial funding rounds in the artificial intelligence segment. Notable deals include:
- Shield AI — $1.5 billion in a Series G round with a valuation of $12.7 billion; defense autonomous systems are firmly becoming mainstream in venture investments.
- Legora — $550 million in Series D with a valuation of $5.55 billion; legal AI remains one of the strongest verticals of the year.
- Temporal — $550 million in Series E for the development of workflow orchestration infrastructure.
- Arena — $200 million in Series B with a valuation of $3.1 billion led by Lightspeed and Khosla Ventures; demand for assessing and testing AI agents is increasing.
- Applied Intuition — reportedly receiving investor offers with a valuation around $30 billion.
An important signal: “lab” valuations are now being received not only by foundational model developers but also by applied AI startups selling solutions for specific industries.
China: DeepSeek, Manus, and a Bet on AI Infrastructure
The Chinese venture market segment is showing significant revitalization:
- DeepSeek closed its first external round — over $12 billion with a valuation exceeding $50 billion, featuring participation from Tencent and CATL, and then led a seed round for robotics startup Winverse AI with a valuation of around $400 million.
- Manus attracted over $500 million led by Boyu Capital and IDG Capital — the first round after Beijing blocked its acquisition by Meta.
- Infinigence AI secured 2.3 billion yuan (about $344 million) in Series C for AI infrastructure development.
- Fujian Fulian Integrated Circuit raised nearly 1 billion yuan in a strategic round with support from government industrial funds.
Deep Technologies: Quantum Computing, Neurointerfaces, and Chemistry
Venture capital is increasingly funding deep tech with a long payoff horizon:
- Oratomic — $475 million in Series B for the creation of fault-tolerant quantum computers.
- Sabi — $50 million in a seed round led by Khosla Ventures for a wearable “brain-AI” interface.
- Albert — $55 million in Series B led by TCV for an AI platform for chemical research.
- Soufflé Therapeutics — an oversubscribed Series B round of $135 million to advance clinical programs; biotech is regaining investor trust.
M&A Deals: IonQ Acquires Elisity
The largest deal of the week in the mergers and acquisitions market is IonQ's agreement to acquire Elisity — a developer of Zero Trust solutions — for up to $1.3 billion in stock, including up to $150 million in milestone payments. The closing is expected in the fourth quarter.
- This is the third major acquisition for IonQ after SkyWater Technology ($1.8 billion) and Oxford Ionics ($1.1 billion).
- The rationale for the deal is to combine post-quantum cryptography with access control for users, devices, and AI agents.
- The market reacted cautiously: IonQ's shares fell amid concerns about capital dilution.
For funds, the deal illustrates that strategic buyers are willing to pay a premium for cybersecurity startups with growing revenue and a corporate customer base.
Europe: Record Fundraising in the UK and Energy Unicorns
According to HSBC Innovation Banking and Dealroom, British venture funds raised a record $6.9 billion in the third quarter across 31 funds — more than four times the average quarterly level of the last two years. British startups attracted $6.1 billion, and over nine months — $23.3 billion, or 35% of all venture investments in Europe.
Among notable European deals:
- 1KOMMA5° (Germany) — €70 million at a valuation of $1.35 billion, the company is preparing to enter the US market and is considering an IPO.
- Epyr — €15 million for industrial heat electrification.
- Ambio (Finland) and OlsAro (Sweden) — seed rounds of around €5 million in the plastic recycling and ag tech segments.
New Venture Funds and Capital Market for LPs
Against the backdrop of capital concentration in mega funds, early-stage managers continue to close new funds:
- Pear VC raised $333 million for its fifth fund focused on the earliest stages.
- DataTribe has begun raising its fourth fund in the cybersecurity sector.
- Monte Carlo Capital has conducted the first close of its second fund at €13 million with a target of €26 million.
In India, startups raised $2.9 billion in the third quarter, led by electric mobility and AI. In Russia, the number of Skolkovo residents exceeded 5,400, and the volume of investments in them reached a record 43.7 billion rubles.
What This Means for Venture Investors
The venture market in October 2026 remains at a record-breaking volume but increasingly selective regarding access to capital. Key takeaways for funds:
- Concentration is the primary risk for portfolios. A third of quarterly capital went to 27 companies, with the average startup competing for an increasingly shrinking market share.
- The Anthropic IPO will set the tone for exits. A successful offering will open the door for other late-stage AI companies, while an unsuccessful one will negatively impact valuations in the secondary market.
- M&A is becoming a full-fledged exit channel, especially in cybersecurity, quantum technologies, and infrastructure.
- Early stages remain the entry point — a 25% year-on-year growth in funding gives seed and Series A funds space for deals at reasonable valuations.
The week’s outcome: startups and venture investments are entering the final quarter of the year at a peak of activity but with an increasing divergence between AI leaders and the rest of the market. The coming weeks — the Anthropic earnings report, TechCrunch Disrupt conference in San Francisco, and closing of major M&A deals — will determine investor sentiment through the end of 2026.