Key agenda items for venture investors and funds on Wednesday, October 21, 2026, include:
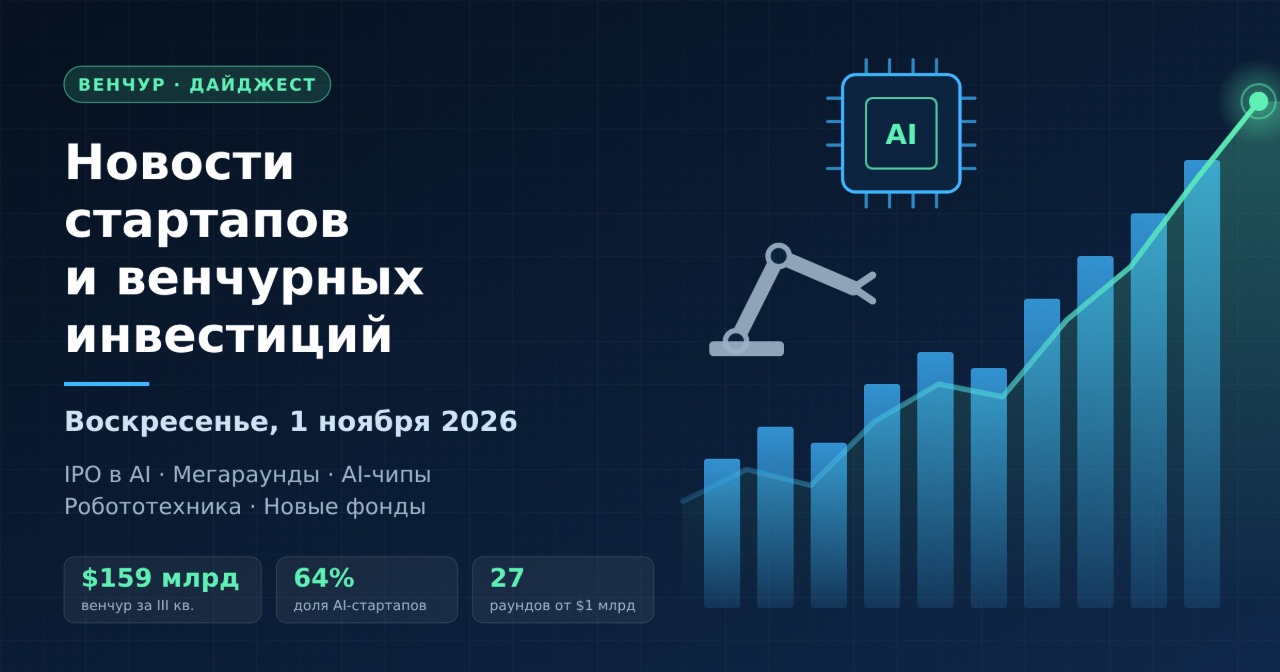
- OpenAI is seeking to raise about $30 billion at a valuation of over $1.4 trillion ahead of the anticipated IPO of Anthropic, expected in mid-November.
- AI infrastructure remains a key magnet for venture capital: Modal, Nscale, and Verda have closed significant funding rounds.
- New unicorns: Town reached a valuation of $1 billion, while Dream Labs raised $90 million for robotics.
- Fintech and defense technologies are showing resilient demand from funds.
- Market risks: Corrections in semiconductors and debt burdens on data centers are restraining valuations.
OpenAI vs. Anthropic: The Battle for Institutional Capital
The most talked-about story of the week is OpenAI's attempt to secure a round of around $30 billion at a pre-investment valuation of $1.4 trillion. According to sources, current shareholders including SoftBank and Abu Dhabi's MGX are participating in negotiations, and UAE funds are collectively discussing investments of up to $10 billion. Interest is also coming from BlackRock and the University of California endowment.
Why OpenAI is in a Rush
- Competition for Money. Anthropic hosted an investor day on October 14 and is preparing for a listing; both companies are appealing to the same sovereign funds and long-only investors.
- Infrastructure Commitments. The companies need a liquidity buffer in case the IPO market softens, delaying their own planned listing in 2027.
- Valuation Growth. The $1.4 trillion valuation is approximately 64% higher than March’s round of $122 billion, which had a valuation of $852 billion, and corresponds to a multiple of about 28x annual revenue of $50 billion.
For the venture market, this is a signal: after Anthropic’s earnings report, both companies will be evaluated against each other, and these figures will set benchmarks for the entire generative AI segment.
AI Infrastructure: Mega Rounds and Revenue Over $1 Billion
The third week of October was marked by significant infrastructure deals. Investors are increasingly differentiating between applied AI and “picks and shovels” — computing platforms with proven revenue.
- Modal Labs — a Series D round of $750 million led by Accel at a valuation of $15.75 billion; the company's annual revenue has exceeded $1 billion.
- Nscale — a convertible round of $3.4 billion led by Third Point Ventures, the largest deal of the month.
- Verda — the Finnish GPU cloud provider raised $189 million in Series B led by Emergence Capital at a valuation of over $1 billion; annual revenue is around $165 million with positive cash flow.
- Salience Labs — $125 million in Series B for photonic computing.
New Unicorns and Applied Artificial Intelligence
Despite the concentration of capital among leaders, applied-level startups continue to secure funding — provided they tackle costly corporate challenges.
Deals from the Start of the Week
- Town — $108 million at a $1 billion valuation: the company develops AI assistants capable of working at the level of entire teams.
- Dream Labs — former NVIDIA researchers raised $90 million to create a general AI “brain” for low-cost robots.
- Legora — $550 million in Series D at a valuation of $5.55 billion; legal AI has cemented itself as one of the strongest verticals of 2026.
- Plinto — €2.9 million pre-seed for AI agents to detect errors in invoices.
Defense Technologies and Cybersecurity
Defense tech has definitively transitioned from a niche segment to the mainstream of venture capital. Shield AI raised $1.5 billion in Series G at a valuation of $12.7 billion, while Anduril conducted an employee tender for $1.3 billion, during which the company's valuation surged from $61 billion to $90 billion in just five months.
In cybersecurity, Armadin stands out: $255 million in Series B led by Andreessen Horowitz and Accel at a $2.5 billion valuation for its autonomous offensive security platform. Investors are betting on protection against AI-enhanced attacks.
Fintech: 35% Growth and Tokenization
The fintech sector is experiencing a robust rebound. Global investments in the industry in Q3 2026 totaled approximately $27.5 billion across 897 deals — a 35% increase compared to the previous year.
- Ramp — $1.85 billion at a $60 billion valuation, one of the largest fintech rounds of the year.
- Valon — $150 million in Series D at a $2.3 billion valuation with participation from Ribbit Capital.
- Spiko — $90 million in Series B led by NEA for scaling tokenized money market funds.
- Capitolis — $120 million in Series E.
Crypto venture remains cautious: in the first 18 days of October, crypto projects raised about $437 million across 27 rounds, with the bulk provided by a post-IPO round from Strive totaling $208 million.
Deep Tech, Biotech and Climate Technologies
Venture funds continue to diversify their portfolios beyond AI applications:
- Oratomic — $475 million in Series B from a syndicate including ARCH Venture Partners, Khosla Ventures, Index Ventures, General Catalyst, and Bezos Expeditions.
- OMass Therapeutics — $310 million in Series C; Soufflé Therapeutics — $135 million in Series B for RNA therapy.
- Voltus — a upsized Series D round of $225 million for a distributed energy platform.
- Icon — $200 million in Series D for robotic construction with participation from Baillie Gifford and BlackRock.
New Venture Funds and Dry Powder
Fundraising continues, though it is concentrated among a limited number of managers. Notable funds from recent weeks include:
- Diffusion ONE — $1.25 billion;
- DCVC VII — approximately $654 million;
- TCGX Asia Life Sciences Fund I — $600 million;
- PSV Tech Fund II — $56 million for pre-seed startups in Northern Europe.
IPO Market and Valuation Risks
2026 has already become a record year for tech IPOs, however, October's volatility has prompted some issuers to pause listings. Companies from the Philadelphia semiconductor index lost over $1.6 trillion in market capitalization in less than two weeks, while CoreWeave bonds, with $50 billion in debt, plummeted sharply. AirTrunk REIT, Firmus, and SB Energy have delayed or withdrawn their listings, with bankers noting that several companies are awaiting the outcome of the Anthropic listing.
Asia Remains Active
In India, the debut of Zetwerk Manufacturing and Tonbo Imaging is expected this week, confirming the resilience of the exit window in emerging markets.
Russia and CIS: Market in Search of the Bottom
The Russian venture market remains under pressure. In the first half of 2026, investment in technology startups totaled approximately $29.3 million — a 62% decrease compared to the previous year, with the number of deals shrinking to 35. Meanwhile, capital is shifting towards M&A deals: 33 transactions valued at around $829 million. Investors are favoring mature companies with proven business models and industrial B2B technologies.
Conclusions for Investors
The startup and venture capital market in October 2026 demonstrates a two-speed dynamic. Capital is concentrating in leaders — AI labs, infrastructure, and defense technologies — while other companies must prove revenue and unit economics. Key benchmarks for the coming weeks include:
- the results of the OpenAI round and final valuation;
- parameters and market reaction to the Anthropic IPO;
- the dynamics of semiconductor stocks and debt market for AI infrastructure;
- the pace of new venture fund fundraising by the end of the year.
For funds, this is a period when discipline in valuations and diversification across sectors become more important than the speed of entry into deals.