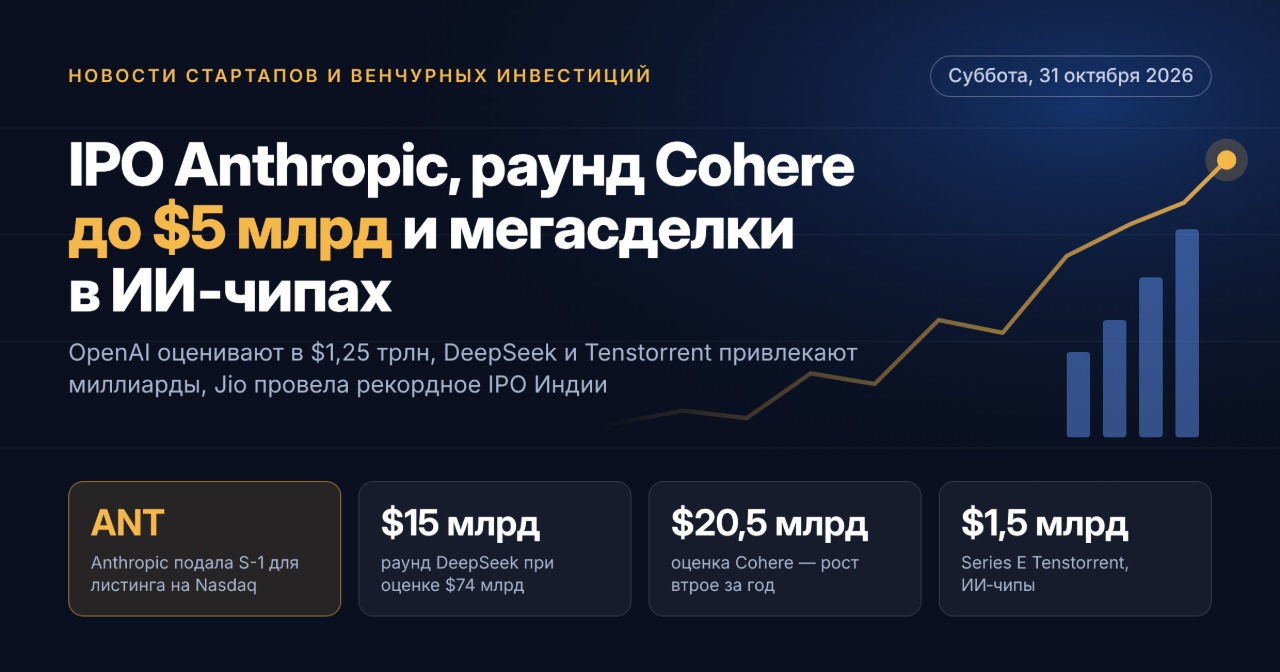
Startup and Venture Capital News — Friday, October 23, 2026: DeepSeek Raises $15 Billion, AI Neo-Labs Surge in Valuation, and IPO Market Awaits Anthropic
The venture capital market wraps up the week with mega-rounds. Chinese company DeepSeek has closed a funding round of approximately 100 billion yuan (around $15 billion), according to Bloomberg, making it the largest deal of the year in Chinese artificial intelligence. In the U.S., investors continue to pour billions into AI neo-labs and applied AI, while public market attention is focused on the possible IPO of Anthropic. This week has prominently highlighted capital concentration, high valuations, and expectations for major exits for venture funds.
Key Highlights for Friday: Major Events of the Week
- DeepSeek — around $15 billion with participation from Tencent, CATL, and Chinese industrial capital.
- Flapping Airplanes — $1 billion at a valuation of $6 billion; valuation quadrupled since January.
- Legora — $550 million in a Series E round at a valuation of $8.8 billion.
- ASI — $325 million at a valuation of $3 billion for AI in critical infrastructure.
- IPO Market — Jio Platforms completes subscription for the largest listing in Indian history, Anthropic may publish its prospectus in the coming days.
DeepSeek: Largest Chinese AI Round of 2026
Initially, DeepSeek aimed to raise around 50 billion yuan, but investor demand allowed them to double the amount. According to Chinese business media, the pre-money valuation of the company is around 500 billion yuan (approximately $70 billion), while the post-money valuation could reach about $84 billion. Key participants in the deal include:
- existing shareholders — Tencent, CATL, IDG Capital;
- new investors — mainly industry capital, including structures from SMIC and Geely;
- target use of funds — expansion of data centers and development of open models.
At the same time, DeepSeek is preparing for an IPO on the Shanghai STAR Market with a listing horizon in 2027. For global venture investors, this signals that China is forming its own financing framework for AI, relying on strategic rather than financial capital.
AI Neo-Labs and Vertical AI: Valuations Growing Faster Than Revenues
The Flapping Airplanes deal illustrates a new trend — a focus on so-called neo-labs that concentrate on research rather than rapid commercialization. The $1 billion round was led by Index Ventures and Lux Capital with participation from Sequoia Capital, GV, and Kleiner Perkins. The company, founded in late 2025, has nothing to sell yet — investors are buying into the team and the thesis of more efficient use of computational power.
On the opposite end is vertical AI with proven revenue. Swedish company Legora, which develops an AI platform for lawyers, raised $550 million under the leadership of Atreides Management. The company has grown from $1 million to $100 million in annual recurring revenue (ARR) in less than 18 months, with participation from all key existing investors — from Accel and Benchmark to General Catalyst.
Applied and "Physical" AI: Capital Flows Into the Operational Layer
Early-week deals show a shift in venture capital from models to companies that integrate AI into real processes:
- ASI (Boston) — $325 million, Series C, valuation $3 billion; lead by Spark Capital, with participation from Andreessen Horowitz and affiliated structures of Citadel Securities. Profile — predictive AI for aviation, energy, and defense logistics.
- Pigment (Paris) — $250 million, Series E, valuation $2.3 billion; round led by Scaleup Europe managed by EQT, the company's ARR exceeded $100 million.
- Arda Industries — $160 million, Series A, valuation $1.5 billion; founder Bob McGrew, former research director at OpenAI, automates the design of assembly lines.
- Eka Robotics — $150 million, Series A, valuation $1.45 billion; co-leaders of the round are a16z and F-Prime.
- Daytona — $60 million, Series B, valuation $1 billion; infrastructure for "sandboxes" for AI agents.
In a single day, four new "unicorns" emerged in the market — a figure characteristic of peak phases of the venture cycle.
Fintech and Alternative Financing Structures
The fintech segment also demonstrates an appetite for large checks. Ramp raised $1.85 billion at a valuation of $60 billion; the round was co-led by Thrive Capital, Founders Fund, Sands Capital, and Avenir Growth. Noteworthy is the deal with Otter.ai: the company received $320 million from the Customer Value Fund managed by General Catalyst without selling equity. The funds are to be repaid with interest as revenue grows. Such non-dilutive instruments are becoming a significant alternative to classic rounds for mature SaaS companies.
Climate Technologies and Energy for Data Centers
The AI boom is fueling demand for energy infrastructure. Californian startup Peak Energy, developing sodium-ion energy storage systems with passive cooling, raised $108 million in a Series B round led by GM Ventures. The funds will be used to enter the data center power market. In France, Elax Énergie secured €30 million for a technology that turns electric water heaters into a flexible resource for the energy system.
IPO Market: Window Open, But Selectively
The public market remains a key factor for venture fund exits:
- Anthropic. According to reports from the Western press, the company is preparing for a possible IPO in November; analysts at Renaissance Capital anticipate the prospectus may be published as soon as this Friday. The latest private round was at a valuation of $965 billion in May.
- OpenAI has ruled out an IPO in 2026 and, according to Bloomberg, is negotiating to raise at least $30 billion at a valuation of around $1.4 trillion.
- Jio Platforms completes its subscription for an IPO of over 30,000 crore rupees on October 23; by the morning of the second day, demand exceeded supply by 3.5 times, with listing expected on October 28.
- Lycia Therapeutics plans to begin trading on Friday after an IPO of $250 million.
However, the number of IPOs in the U.S. is a third lower than in 2025, making the success of large listings critically important for the liquidity of the entire industry.
Macro Context: Record Nine Months for Venture Capital
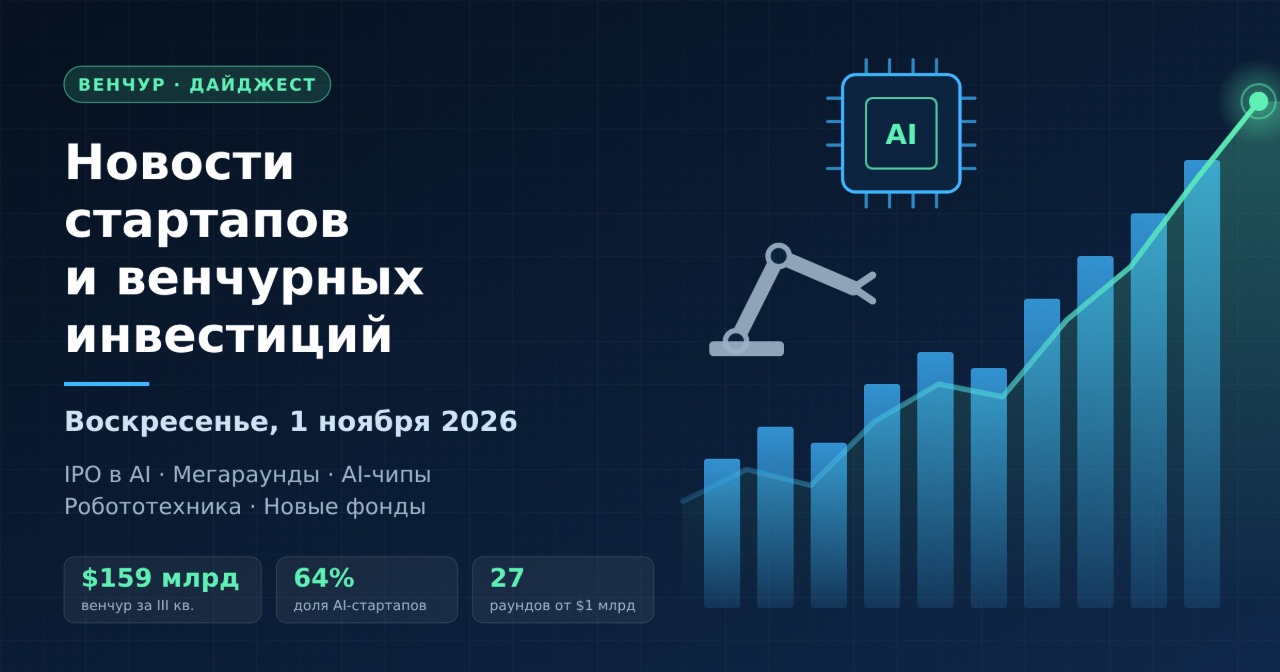
According to Crunchbase data, global venture investments reached $159 billion in the third quarter of 2026 — a 25% decrease from the second quarter but a 53% increase from the previous year. Key figures include:
- $102 billion, or 64% of all venture capital, went to AI companies;
- 27 rounds of $1 billion or more — an absolute record for the quarter;
- $679 billion over nine months — the highest in history;
- 57% of quarterly volume was attributed to American startups.
Russia and the CIS: Market Contraction and Focus on Government Funds
The Russian venture market is moving in the opposite direction. According to the Moscow Venture Fund, in the first half of 2026, the volume of venture investments shrank by 48% to 4.6 billion rubles, and the number of deals fell by 45% to 54. Support for startups is primarily provided by development institutions: at the Moscow Startup Summit, the MVF signed agreements worth 250 million rubles with expected co-investments of about 1 billion rubles. Among new instruments is the specialized fund by FRII for startups in the information security sector and the "Creative Venture" fund of 1 billion rubles.
What This Means for Venture Investors
- Concentration Intensifies. Capital is gathering around a small number of leaders, and competition for stakes in top rounds is sharpening.
- Quality of Revenue Becomes Crucial. Companies with an ARR above $100 million, like Legora and Pigment, receive a premium on their valuation.
- Role of Non-Dilutive Financing Grows for mature startups aiming to preserve founder equity.
- IPO of Anthropic Will Be an Indicator for the entire queue of tech listings for the remainder of the year.
The venture market enters the final quarter of 2026 with record volumes but heightened sensitivity to overheating risks. For investors and funds, the key question over the coming weeks will be whether the public market can validate the valuations formed in private rounds.