Startup and Venture Capital Highlights for October 22, 2026: OpenAI's Capital Race, Ramp and Modal Mega-Rounds, New Unicorns Pigment and Daytona, IPO Preparations, and Venture Fund Activity in Europe, Asia, and the CIS
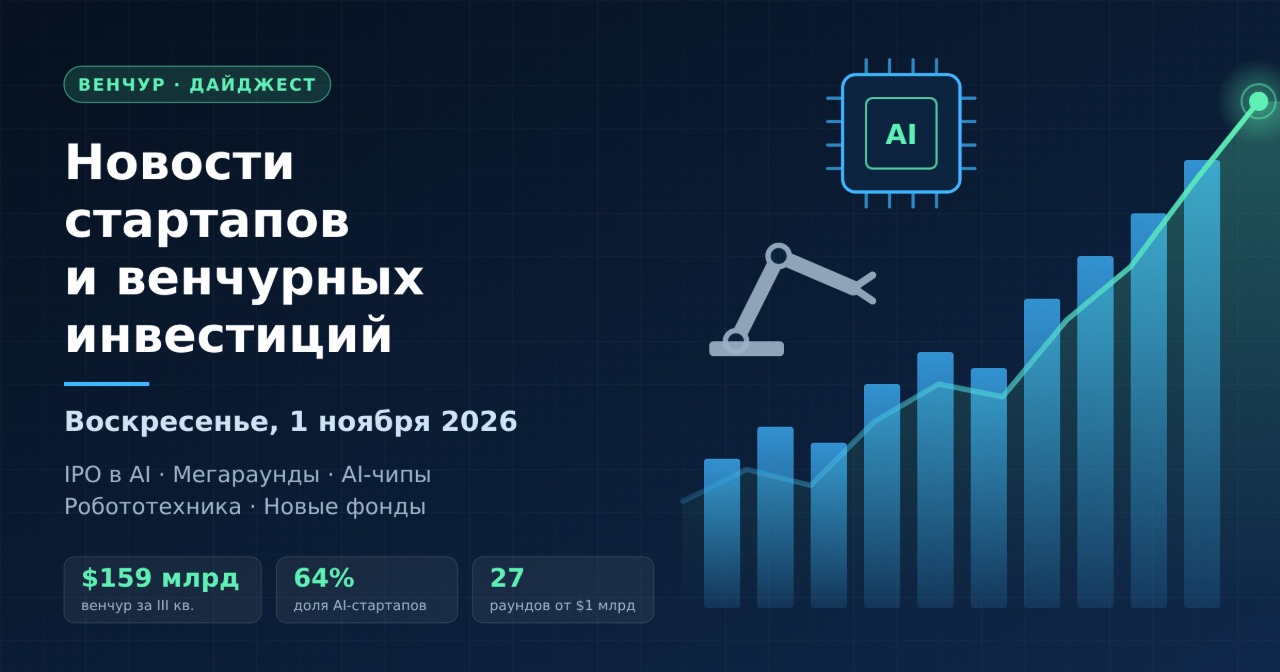
The venture market enters the last decade of October 2026 with a rare concentration of capital. The largest private companies in the world are competing for investor dollars ahead of the anticipated IPO of Anthropic, while the AI infrastructure layer continues to be overvalued at an unprecedented pace. In the 30 days leading up to October 18, startups around the globe announced approximately 600 funding rounds with a total disclosed volume of around $32 billion. For venture investors and funds, the key question of the week is where the line is drawn between justified growth premiums and overheated valuations.
Key topics of the day for investors:
- OpenAI accelerates a round at ~$30 billion with a pre-money valuation of around $1.4 trillion ahead of Anthropic’s IPO.
- Mega-rounds in fintech and AI clouds: Ramp valued at $60 billion, Modal at $15.75 billion.
- New unicorns: Pigment, Daytona, and Arda join the club of companies valued over $1 billion.
- IPO window: biotech in the US, record placement of Jio Platforms in India, and withdrawal of applications from weak issuers.
- Defense technologies and biotech strengthen their positions as the second most significant areas for venture investment.
1. OpenAI vs. Anthropic: Capital Race Ahead of the Year’s Major IPO
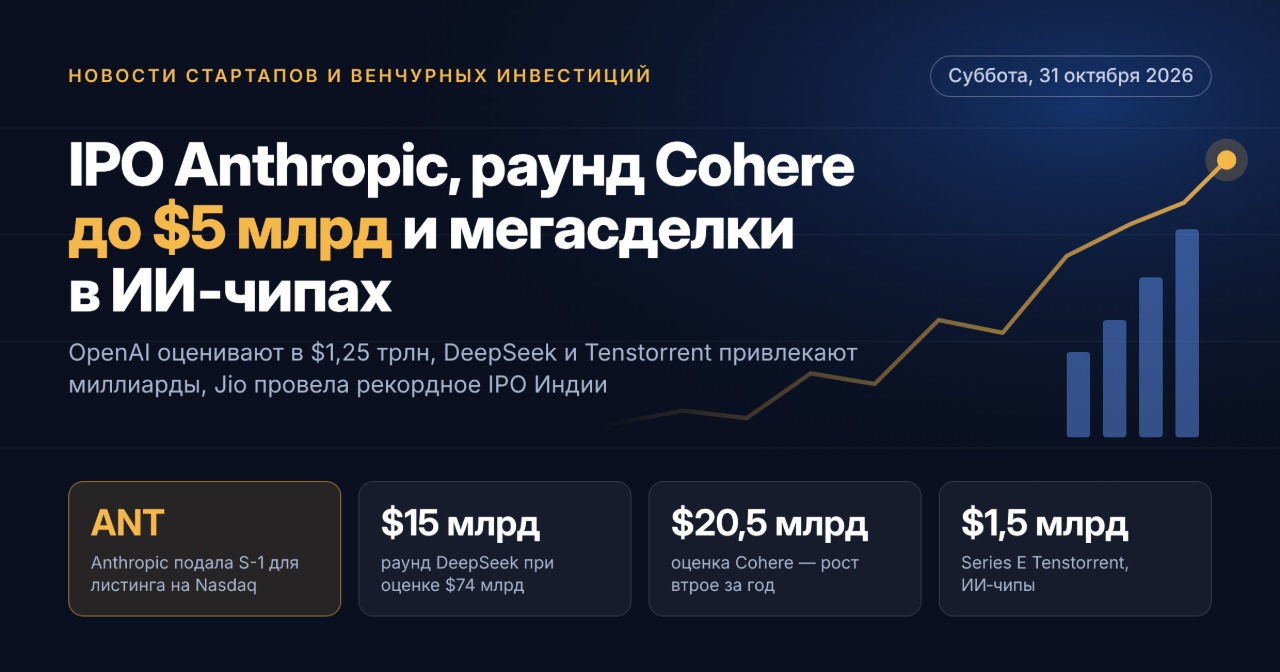
The central theme for the venture market is OpenAI's pursuit of a new valuation ahead of its main competitor's public debut. According to sources familiar with the situation, the company is accelerating a raise of about $30 billion with a valuation of around $1.4 trillion before factoring in new money. Negotiations involve SoftBank, Abu Dhabi’s MGX, and other existing shareholders.
Why This Matters for Investors
- The last valuation for OpenAI was $852 billion following a record $122 billion round in March 2026. The new target implies an approximate 64% growth over seven months.
- The company set the round's price itself, deviating from the classic lead investor negotiation model.
- The public offering for OpenAI has been postponed at least until 2027, making this round effectively a "bridge" to the IPO.
- The annual revenue for OpenAI surpassed $40 billion on an annualized basis by summer.
Simultaneously, some investors in Anthropic are reportedly discussing a target of around $1.5 trillion for its anticipated debut on the stock exchange in mid-November. For the entire market, this means creating a public benchmark that later-stage AI companies will use as a reference point.
2. Ramp: Fintech Unicorn Valued at $60 Billion
The corporate expense management service Ramp raised approximately $1.85 billion with a pre-money valuation of about $60 billion. The round was led by Dragoneer Investment Group and Thrive Capital, with a significant check also written by Founders Fund. Just in June, the company's valuation was $44 billion.
- The client base consists of over 70,000 companies.
- Growth strategy includes embedding AI agents into financial processes and possible training of proprietary models.
- Context: Ramp's main competitor, Brex, was sold to Capital One for $5.15 billion in 2026, making Ramp the undeniable leader in the independent segment.
3. AI Infrastructure: The Fastest-Growing Asset Class
The AI infrastructure layer remains the principal magnet for venture capital. Investors are paying premiums not for chatbots, but for computing, cloud services, and tools for AI agents.
Modal: Valuation Up 3.4 Times in Five Months
The cloud platform Modal closed a Series D round at $750 million with a post-money valuation of $15.75 billion. Accel was the lead investor, joined by Kleiner Perkins and all existing shareholders. The company’s annual revenue growth rate has surpassed $1 billion, while in May, at the Series C round, its valuation was $4.65 billion.
Daytona: "Cloud for Agents" Becomes a Unicorn
The startup Daytona raised $60 million in a Series B round at a valuation of $1 billion. The company is building a specialized cloud environment where AI agents receive isolated "sandboxes" to operate in mere milliseconds.
Inference Chips
According to industry analytics, the median valuation for AI chip developer startups has increased approximately ninefold over the past two years, raising the bar for future exits and increasing risk for funds entering at late stages.
4. New Unicorns and Applied AI
Beyond infrastructure, venture funds are actively financing applied AI solutions for the corporate sector and industry.
- Pigment (France) — $250 million at a $2.3 billion valuation; round led by Scaleup Europe Fund with participation from Nvidia. Annual recurring revenue exceeded $100 million and doubled within a year.
- Arda (USA) — $230 million at a $1.5 billion valuation from Altimeter Capital, Accel, and Khosla Ventures. The company, founded by former OpenAI research lead Bob McGrew, automates manufacturing line design.
- Different (USA) — $48 million in seed funding for a full-cycle marketing AI system.
- Leena AI — strategic investment from IBM Ventures in agency AI for HR, IT, and finance.
5. Fintech and Stablecoins: Infrastructure for the “Bot Economy”
The fintech segment demonstrates steady early-stage activity:
- Mural — $15 million in Series A led by Tether for a platform integrating fiat currencies and stablecoins.
- ScribeUp — $13 million for banks seeking to control the management of customer recurring payments.
- Fragment — $12 million to automate financial operations for vertical AI companies.
- Prism Data — $20 million for credit scoring based on open banking data.
6. Biotech and Defense Technologies: An Alternative to AI Concentration
Biotech
- Swiss startup Nouscom — $135 million in Series D with participation from M Ventures and the European Investment Bank.
- Estuary Biotherapeutics — $93 million in Series A led by RA Capital Management for gene therapy for kidney diseases.
Defense Technologies
- Destinus acquired the Dutch startup Perciv AI, which develops radar perception for GNSS-denied conditions.
- British company Skyfly raised $10 million in a seed round for a hybrid drone.
- According to industry surveys, nearly all British defense companies expect to attract external capital.
7. IPO Market: The Window is Open, but Selectively
Public markets remain accessible for quality issuers; however, investors are rigorously filtering out weak stories.
- Lycia Therapeutics prepares for an IPO on Nasdaq of approximately $250 million with a share price in the range of $16–18; trading is expected to commence at the end of the week.
- Jio Platforms is conducting the largest IPO in Indian history: subscription is open from October 21–23, with listing planned for October 28.
- Klook withdrew its application for an approximately $400 million US IPO, while several small issuers reduced the size of their offerings.
8. Russia, CIS, and Europe: Local Venture Agenda
- Indie GO Fund II — a new Russian fund for gaming studios with a target volume of 5 billion rubles; the first closing is scheduled for Q4 2026, with a strategy focused on subsequent IPOs for portfolio companies.
- Moscow Venture Fund has signed agreements with tech companies for 250 million rubles with expected co-investment volume of about 1 billion rubles.
- Paidax (Kazakhstan) — $1 million with participation from DOMiNO Ventures; the platform is now eligible to trade digital assets on KASE.
- Europe: Spanish Enzo Ventures closed its second fund at €20 million for pre-seed deals, and the growth team at Partech has spun off into a standalone investment firm.
9. What This Means for Venture Investors and Funds
The startup and venture capital market in October 2026 is following a "power law" trajectory: capital is concentrating among a narrow circle of AI leaders, while valuations of infrastructure companies are being reassessed significantly over just a few months. This creates several practical takeaways for funds:
- Valuation discipline is becoming a key factor for returns: the entry multiples for late stages are already pricing in years of flawless growth.
- Anthropic’s IPO will set a benchmark for the revaluation of the entire AI sector — both in terms of growth and correction.
- Diversification into biotech, defense technologies, and fintech reduces portfolio dependence on a single theme.
- Early stages remain the area of greatest asymmetry: this is where future unicorns of applied AI will take shape.
In the coming weeks, investor attention will be drawn to the closing round of OpenAI, the parameters of Anthropic's offering, and the results of the Jio Platforms listing — three events that will set the tone for the global venture market for the end of 2026.