Key Points for Venture Investors:
- Nscale filed an IPO prospectus with the NYSE, with a valuation target of up to $35 billion.
- Holtec Nuclear postponed its offering of up to $900 million due to market conditions.
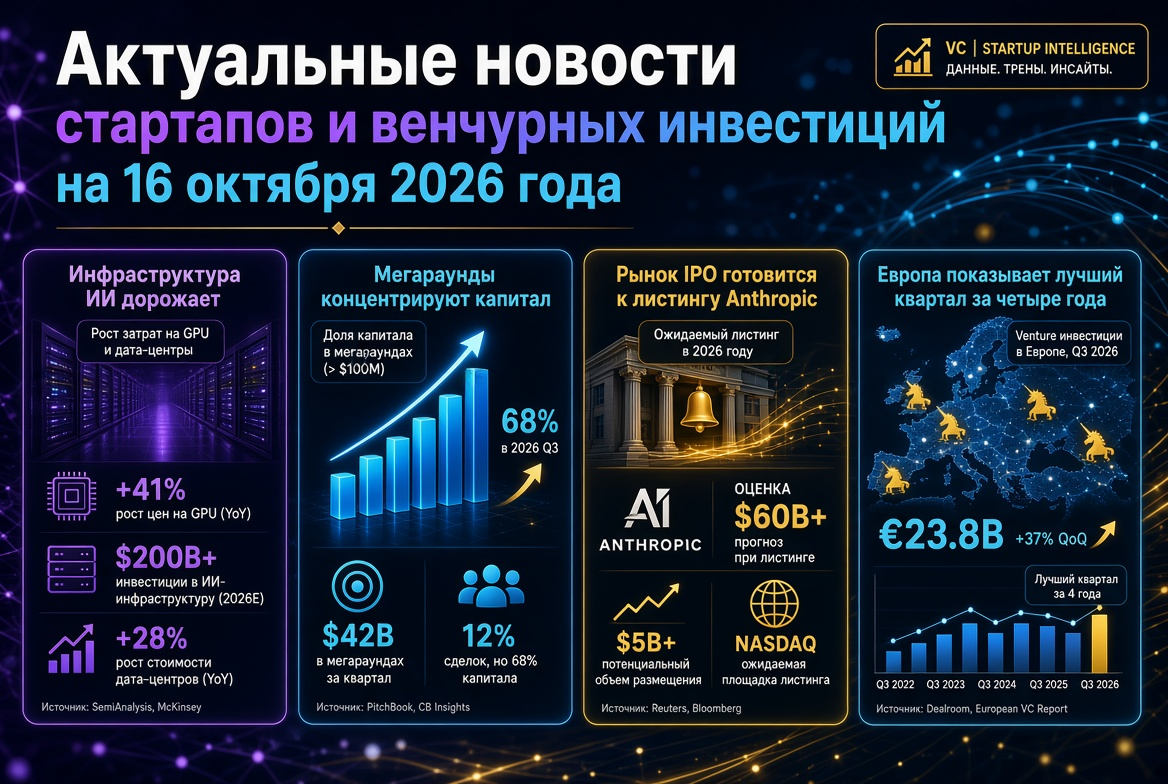
- OpenAI has pushed its IPO to 2027, while investors propose a round at a valuation of $1.2 trillion; Anthropic remains on track for Nasdaq.
- Emulate is preparing a seed round of up to $700 million, and Euclyd raised €200 million in a Series A round.
- Crux AI is securing a $22 billion loan backed by chips, and Bloom Energy is seeking $25 billion in project financing.
- An Indian alliance of deep tech investors has committed to invest $3 billion, while CATL is launching a venture fund of $860 million.
Nscale: A Crucial IPO Test for AI Infrastructure
The British neo-cloud provider Nscale filed an IPO prospectus with the SEC on Friday and intends to trade on the NYSE under the ticker NSCL. The underwriting will be handled by Goldman Sachs, J.P. Morgan, and Morgan Stanley. Revenue for the first half of 2026 grew to $140.6 million from $10.4 million the previous year, while net loss widened to $1.02 billion. Remaining contract obligations total $56.4 billion, yet more than half of the revenue was sourced from a single client. According to media reports, the company aims to raise up to $3 billion at a valuation of up to $35 billion—compared to $14.6 billion in the March Series C round. Concurrently, Nscale secured a convertible loan from Nvidia.
For venture funds, this is the first autumn indicator of how public investors will assess a capital-intensive model with contracted demand, a high concentration of clients, and reliance on a single GPU supplier.
Holtec and the IPO Window: Selectivity Over Euphoria
Holtec Nuclear, previously viewed as the leading IPO of September, has postponed its offering. Market conditions are unfavorable: X-energy is trading about 37% below its April offering price, while Standard Nuclear is down 21%. The IPO window hasn't closed but has narrowed:
- This week, Bamboo Insurance ($665 million at a $3.3 billion valuation) and defense materials producer Amaero ($53 million) are expected;
- Biotech company Electra Therapeutics, which raised $350 million, is trading approximately 12% below its offering price;
- Motive has withdrawn its IPO application and has secured over $1.3 billion in growth funding from General Catalyst—private equity is replacing the exchange;
- Revolut is considering a dual listing in New York and London with a valuation of up to $200 billion.
A "Pause in AI" and the Fed Rate: A Dual Filter for Valuations
Anthropic's CEO Dario Amodei published an essay advocating a coordinated slowdown in enhancing model capabilities. This view was supported by Sam Altman and leaders from other major tech companies. The market reacted with a sell-off in semiconductors, but by the end of the week, the Nasdaq gained 0.7%, while the Dow lost 1.7%.
Industry analysts highlight the implications for venture investments: longer model release cycles, a potential shift in data center commitments, extended exit timelines, and additional pressure on LPs. Competition is shifting from "raw" performance to distribution, reliability, and cost—in favor of the large players. At the same time, suggestions are emerging to regulate owners of more than 5% of computing power in a manner similar to systemically significant banks.
OpenAI and Anthropic: Trillion-Dollar Valuations, Different Paths
Investors have proposed a round for OpenAI at a valuation of approximately $1.2 trillion—41% higher than the March $852 billion when the company raised $122 billion. According to media reports, there are no formal negotiations yet; some proposals involve stock sales by employees. Annual revenue has exceeded $40 billion, with an IPO expected in 2027. Anthropic, valued at $965 billion in May, is still preparing marketing for a Nasdaq placement in mid-October. Its listing will set a public multiple for the entire AI sector.
Mega-Rounds and New Unicorns: Capital Concentration
- Temporal: $550 million Series E at a valuation of $12.55 billion; a platform for AI agents.
- Fab2: $500 million Series A for the mass production of compact chip factories.
- Suniva: $835 million in debt and equity for solar cell production in the US.
- Ridgeline: $250 million at a valuation of $1.45 billion; Cornelis Networks: $205 million for AI networking solutions.
- Penelope Health: $100 million for automating administrative processes for physicians.
A week earlier, Cognition raised $2 billion at a valuation of $48 billion, while Boring Company raised $3 billion at $23 billion. Median rounds A and B remain moderate, with a widening gap between category leaders and other startups.
Debt Instead of Equity: Chips and Energy as Collateral
Funding for AI infrastructure is increasingly shifting to the credit market. A consortium of ten banks is providing $22 billion secured by TPU and client contracts for Crux AI—a cloud project involving Blackstone and Alphabet with $5 billion in equity. Bloom Energy has secured $25 billion in project financing for energy supply to data centers from Brookfield. Nvidia will invest $2 billion into Brookfield’s $10 billion AI infrastructure fund. For venture funds, this means less dilution in portfolio companies but a higher sensitivity to rates.
M&A: Signed Doesn't Mean Closed
Deals remain a second channel of liquidity, though closing timelines are extending. Nvidia's acquisition of Hugging Face for $12.9 billion is expected to close only in the first half of 2027. Signed but not closed deals include Visa — BioCatch ($2.4 billion), Analog Devices — Alif Semiconductor ($1.35 billion), Bending Spoons — Miro ($1.36 billion), and Dynatrace — Arize AI ($915 million). SoftBank has agreed to buy the Robotics and AI Institute, with the deal under review in the US. SPACs are making a return: nuclear technology developer HGP is merging with Meshflow at a valuation of $1.2 billion.
Europe, Asia, and Emerging Markets
- United Kingdom: Emulate, founded in August by alumni from Google DeepMind, is discussing a seed round of up to $700 million at a valuation of around $3.7 billion; leading investors include Index Ventures and Lightspeed. ElevenLabs is preparing a Series E of over $500 million with possible involvement from the Scaleup Europe Fund.
- Netherlands: Euclyd raised €200 million in a Series A round for inference chips; among the round’s leaders is Samsung.
- India: The India Deep Tech Alliance has committed to investing $3 billion, with $250 million deployed in the first year.
- China: CATL is creating a venture fund of $860 million for AI and robotics; its robotaxi division Hello has raised about $100 million.
- Latin America: Brazilian VOLL has secured $140 million from Warburg Pincus.
What This Means for Venture Investors and Funds
- Exits are shifting. The postponement of OpenAI’s IPO and Holtec's pause extend the liquidity horizon—DPI planning needs to be reassessed.
- Nscale and Anthropic will set multiples. Their reception by the public market will define late-stage valuations for 2027.
- Regulatory risk has become an investment factor. Security audits and potential computational limits must be factored into due diligence.
- The capital structure is changing. Debt secured by chips and contracts reduces dilution but requires sustainable unit economics at a 4% rate.
- Team premium has reached its limit. Seed rounds in the hundreds of millions without a product raise the bar for the next round and the risk of a down-round.
The venture market remains liquid, but it demands proven demand, control over scarce resources, and capital discipline. These criteria will shape the news surrounding startups and venture investments until the end of the third quarter.