Oil Market: First Weekly Correction in Three Weeks
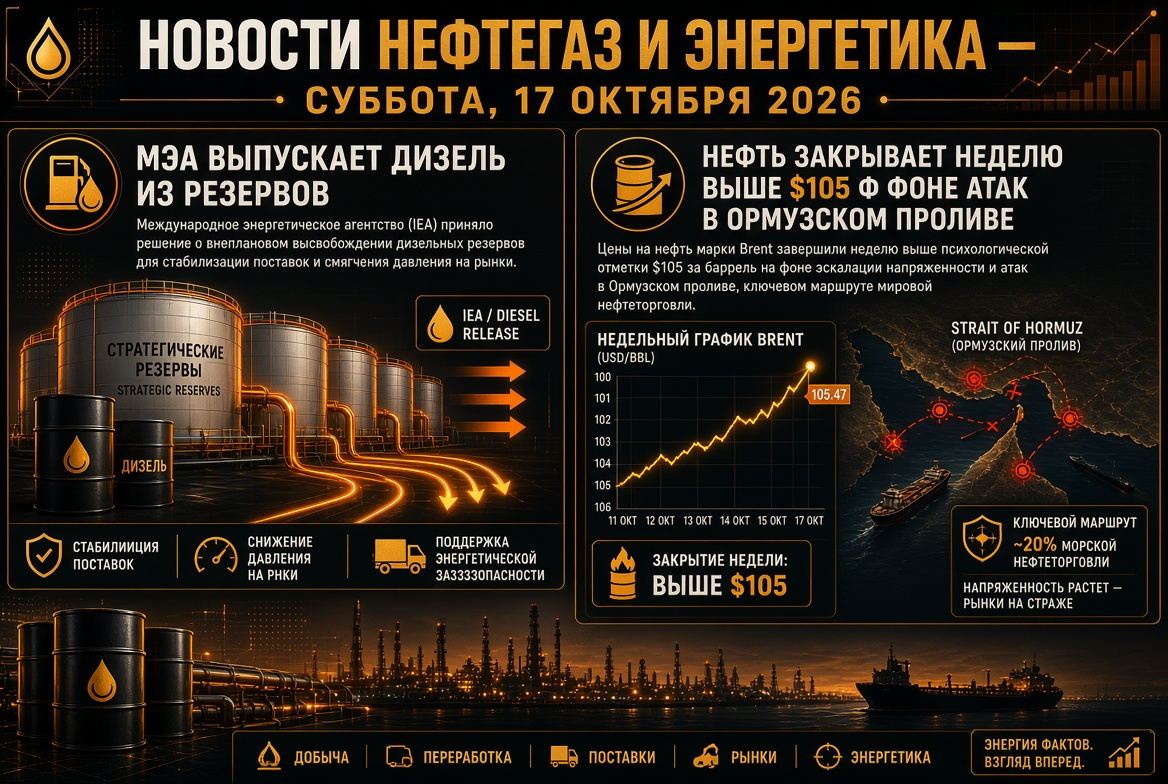
On Friday, oil prices fell for the third consecutive session: Brent dipped to $102.5–103.5 per barrel, while WTI fell to $100, briefly going below this mark. For the week, Brent is down about 2%, although on Monday, prices had rallied to $108 — nearly a four-month high.
- Wednesday: a drop of nearly 3% to $105.7 — the steepest in three weeks — following reports of a partial restart of the Saudi East-West pipeline.
- Thursday: Brent closed at $104.82, and WTI at $101.91 per barrel.
- For the month: WTI has gained about 18–19%, while Brent has increased by approximately 13%; oil prices are more than 50% higher compared to the levels of a year ago.
Analysts agree that the fundamental picture does not justify a prolonged decline of Brent below $100. The futures curve remains in deep backwardation: the December contract is nearly $5 cheaper than the November contract, indicating that the market is paying a premium for immediate delivery.
Middle East: East-West, Red Sea, and Hormuz
The East-West pipeline, with a capacity of up to 7 million b/s, is the main bypass of the Strait of Hormuz, through which up to 5 million b/d have flowed in recent months. After drone attacks, three pumping stations were damaged, and shipments from Yanbu were halted. Riyadh is expected to restore about half of the capacity within a few days; complete recovery will take five to six weeks.
- Alternative routes: Saudi Arabia is offering additional batches to Asian refineries via ship-to-ship transfer at Oman’s Sohar port.
- Red Sea: Houthi forces have taken control of Mocha, Perim, and Hanish islands and declared a blockade of Saudi ports; on Thursday, there were renewed strikes exchanged across the border.
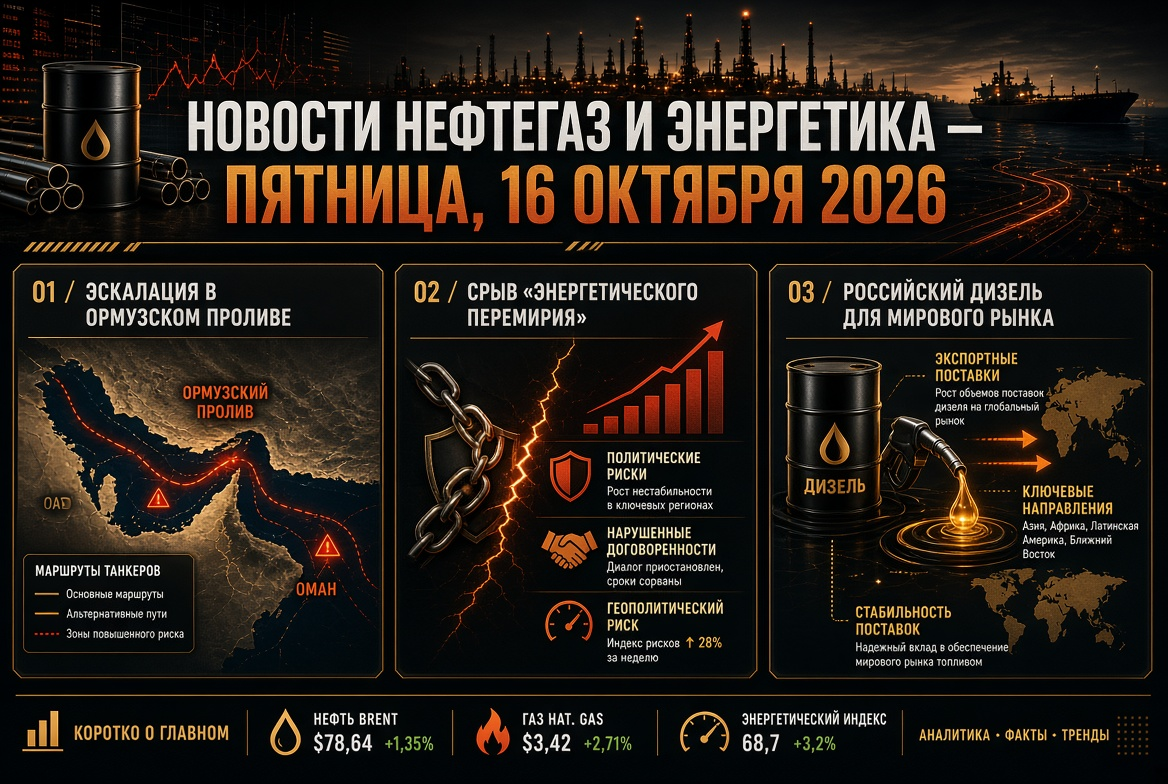
- Hormuz: the strait is effectively closed to commercial shipping, there are no direct negotiations between the US and Iran, and the maritime blockade of Iranian ports remains in place.
- Production: Saudi Arabia reported a production decline in August to the lowest level since 1990.
The IEA warns that supply disruptions are already forcing consumers to reduce their demand for oil.
Oil Products and Refineries: Diesel Remains the Epicenter of Scarcity
- The diesel crack spread in the US reached a record $117.97 per barrel on Wednesday; European gasoil is at historical peaks.
- Exchange-traded diesel in New York is around $5.05–5.25 per gallon; the retail price in the US is a record $6.23 per gallon, with gasoline at $4.32.
- Distillate stocks in the US have risen for the third consecutive week: +1.6 million barrels to 107.9 million barrels — the first signal of cooling.
Diesel in Europe is approximately 70% more expensive than February levels. For refineries outside conflict zones, this is a period of super margins, while for fuel companies, aviation, and logistics, it poses a shock in costs.
Gas and LNG: Europe Enters Heating Season with 68% Stock Levels
TTF futures rose by 1.5–2% on Friday, to €77–78 per MWh, down from €82 on Wednesday; year-on-year, gas in Europe has increased by approximately 140%. EU storage is filled to about 68% — 16 percentage points below the five-year average and near two-decade lows.
- Qatar: the force majeure on LNG supplies has been extended to November; about 17% of Ras Laffan's capacity is offline, with repairs estimated to take three to five years.
- Asia: spot LNG prices are $26–28 per million BTU — the highest since 2022; demand for LNG in the region is expected to decrease by 3–10% by year-end, with some South Asian buyers rejecting costly offers.
- Norway: scheduled maintenance is temporarily reducing pipeline supplies.
- USA: Henry Hub is around $2.86 per million BTU; the record spread supports American LNG exporters.
Russia and Ukraine: Energy Ceasefire Not Confirmed, Fuel Exports Restricted
The agreement announced by Washington on September 14 to cease strikes on energy infrastructure is not being implemented: in the past week, refinery attacks occurred in Syzran and Yaroslavl, and strikes continue on Ukrainian infrastructure. Moscow called the idea 'good,' while Kyiv is ready for de-escalation with partner guarantees.
- The export ban on diesel for producers, according to industry sources, is extended to the end of October; for non-producers, it remains in effect until January 31, 2027.
- A full ban on gasoline exports is in place until January 31, 2027; the export of aviation fuel is restricted until November 30.
- Six major Russian refineries have reduced output following drone strikes.
For the global oil product market, the absence of Russian diesel is one of the factors contributing to the record premiums in middle distillates.
Asia: India and China Share Available Barrels
Russian oil imports to India in August fell to about 2.1 million b/d compared to 2.7–2.8 million b/d in July: repairs at refineries, limited availability of crude, and aggressive purchases by Chinese processors played a role. The retreat of Brent from its peaks provides India some breathing room — the rupee hovers around 95.8 per dollar. Conversely, the yuan has strengthened to a four-year high, lowering energy import costs for China.
Electricity, Renewables, and Nuclear: Structural Shift Accelerates
- Renewables: according to the IEA, renewable generation will increase by approximately 1000 TWh annually until 2030, with over 600 TWh coming from solar generation; the share of low-carbon sources in global electricity is set to rise from 42% to 50%.
- Nuclear: uranium is around $90 per pound; the US and Saudi Arabia signed a peaceful nuclear agreement, and South Korea has completed the Saeul 3 energy block. Meanwhile, summer droughts have limited operations at nuclear power plants in Europe.
- Bottleneck: delivery times for large gas turbines exceed the construction cycle of the power plant itself.
Expensive gas improves the economics of renewables and storage, yet rising rates are increasing capital costs for grids and new projects.
Coal: Insurer of Asia’s Energy Systems
Coking coal in Newcastle remains around $145 per tonne. Northeast Asia is replacing expensive LNG with coal and nuclear generation, supporting demand for exporters such as Australia, Indonesia, Russia, and South Africa. The long-term trend remains unchanged: according to the IEA, the share of coal in global generation will decrease from 34% in 2025 to 27% by 2030, prompting major producers to delay investments in new mines.
Macroeconomics: Rates Rising in Response to Energy Inflation
On September 16, the Fed raised the rate by 25 basis points to 3.75–4.00% — the first increase since 2023; the Bank of Japan also raised rates on Friday. The yield on 10-year US Treasuries is around 4.95%. The number of drilling rigs in the US, according to the latest data, has risen to 591 (450 oil and 132 gas) compared to 539 a year ago: shale companies are responding to prices, but cautiously.
What to Monitor for Investors and Energy Sector Participants
- The actual restart of the East-West pipeline and the resumption of shipments from Yanbu.
- Shipping through the Hormuz and Bab-el-Mandeb straits, new strikes on infrastructure.
- The status of the energy ceasefire between Russia and Ukraine and the condition of Russian refineries.
- The official extension of the diesel export ban from Russia.
- The dynamics of TTF, Europe’s gas storage injection rates, and competition with Asia for LNG.
- Diesel crack spreads and weekly inventory statistics in the US.
The baseline scenario for the coming days is Brent in the range of $98–108 per barrel with high sensitivity to news from the Middle East. Oil products and gas remain the most stressed segments of the global energy market.