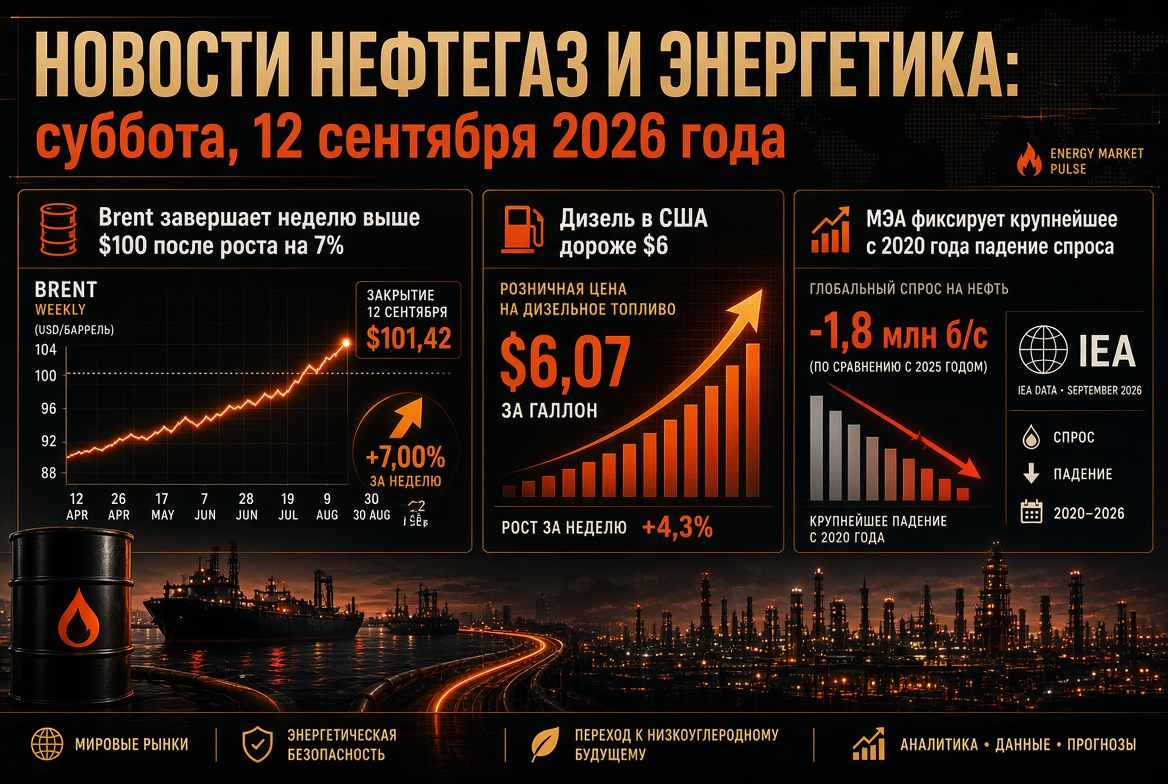
Oil Market: Brent and WTI Decline but Maintain Above $100
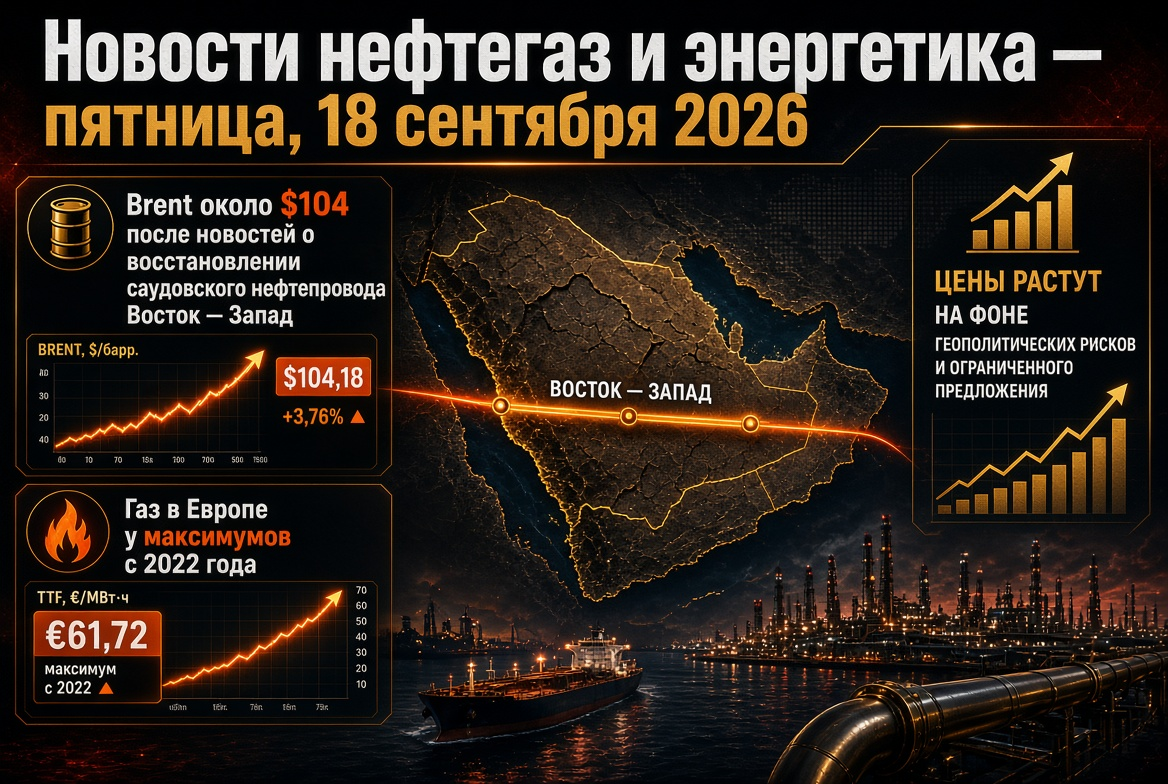
By Thursday evening, Brent was trading around $104 per barrel, and WTI was in the $101–102 range. Earlier in the week, Brent peaked at $109; over the month, the benchmark added about 14%, with a yearly increase of over 50%. Key drivers include:
- Saudi Arabia: The kingdom expects to restore approximately half of the East-West pipeline capacity damaged by drone attacks last week within a few days, reaching full capacity in about six weeks. The route, with a capacity of up to 7 million b/d, is the primary bypass of the Strait of Hormuz.
- Hormuz: According to the U.S. Energy Department, around 18 million barrels of oil and oil products passed through the strait at the beginning of the week; Riyadh is increasing shipments with support from U.S. military.
- U.S. Stocks: Commercial crude oil inventories fell by 0.64 million barrels to 423.4 million—less than market expectations, although an industry estimate indicated a rise of 7.1 million barrels prior.
- Supply Risks: The Houthis' advance toward the Bab el-Mandeb Strait, halts in several fields in Libya amid force majeure threats, and Tehran's refusal to negotiate with Washington until its conditions are met.
Supply and Demand: OPEC and IEA Assessments
- Saudi Arabia reported to OPEC a decline in production in August to 6.24 million b/d—the lowest since 1990; secondary sources estimate the level closer to 7.3 million b/d.
- The IEA has downgraded its forecast for global supply in 2026 to 100.7 million b/d (down 5.7 million b/d year-on-year).
- Global demand for oil is expected to decrease by 2.5 million b/d in 2026, with a recovery of 2.6 million b/d anticipated in 2027.
- Observed global stocks fell by another 95 million barrels in August; the cumulative reduction since February is 507 million barrels.
Refined Products and Refineries: Diesel is the Main Market Deficit
The crisis is increasingly shifting from crude oil to refined products. Wholesale diesel prices in the U.S. surpassed $200 per barrel at the beginning of September—almost double pre-war levels, with retail prices reaching a record $5.90 per gallon. In the EU, diesel costs about €2.04 per liter, close to the April record.
- Net diesel exports from the Gulf countries in August averaged about 390,000 b/d—one-quarter of pre-war volumes; combined shipments from the Gulf and Russia are 1.6 million b/d below February levels.
- Global refining reached a summer peak of 81.4 million b/d, but a decrease of 2.6 million b/d is expected for the year.
- Refinery margins in the Atlantic basin are at record levels; profitability in Singapore is constrained by high freight costs.
For refineries outside the conflict zone, this is a period of super profits; for fuel companies and consumers, it represents a cost shock.
Gas and LNG: Europe Enters Winter with Low Stocks
TTF futures fell to €76–77 per MWh on Thursday after attempting to secure levels above €80; earlier in the week, prices approached €82—the highest since late 2022. Year-on-year, gas prices in Europe have increased by over 130%. EU storage is only about 68% full—one of the lowest levels in two decades for this date. Pressures are arising from limited supplies of Qatari LNG, scheduled maintenance in Norway, and competition with Asia for cargoes. Henry Hub in the U.S. remains around $2.90 per MMBtu—record spreads support U.S. LNG exporters.
Geopolitics: Energy Truce Between Russia and Ukraine in Question
On September 14, the U.S. President announced that Moscow and Kyiv had agreed to cease strikes on energy facilities, linking the rise in diesel prices primarily to this conflict. Kyiv stated that the agreement is not finalized and is only possible with partner guarantees; Turkey is acting as the mediator. Previous attempts at similar truces have proven short-lived. If the regime is implemented, the recovery of Russian refining could reduce the premium on distillates. The sanctions regime remains unchanged.
Russia: Fuel Export Restrictions Remain in Place
- The ban on gasoline exports is in effect for all market participants until January 31, 2027.
- The ban on the export of diesel, bunker fuel, and gas oils for producers has been extended until September 30; the market awaits a decision for October.
- According to the IEA, over the past eight months, Russian refineries have been subjected to effective strikes approximately every three days; since July, the country has begun to import refined products.
- The Urals discount to Brent has nearly disappeared amid reduced shipments and high demand in Asia.
Asia: China Outbids India in the Race for Russian Oil
Russian oil imports into India fell by approximately 26% in August to around 2.1 million b/d, down from a record 2.8 million b/d in July; total imports of crude have decreased to 4.6 million b/d. Chinese refiners are aggressively purchasing cargoes, replacing Middle Eastern volumes, while India partially compensates for losses with Venezuelan oil. The crude shortage at Indian refineries threatens a reduction in diesel and gasoline exports—an additional factor of tension in the Asian petroleum products market.
Electricity, Renewables, and Coal: Insurance and Structural Shift
- Coal: Energy coal in Newcastle is around $145 per ton (+12% month-on-month, +40% year-on-year). The LNG deficit adds about 70 million tons of demand for Asia in 2026; coal generation in Japan has increased by 11%. Major producers are not sanctioning new mines, viewing the surge as cyclical.
- Renewables: By the end of 2025, renewable sources surpassed coal for the first time in global generation (33.8% vs. 33.0%), and in April 2026, wind and solar exceeded gas in electricity output for the first time (22% vs. 20%). Solar capacity additions in 2025 reached a record 647 GW.
Expensive imported gas strengthens the economics of renewables and energy storage, but in the short term, coal and nuclear power ensure grid balance.
Macroeconomics: The Federal Reserve Responds to Oil Inflation
On September 16, the Fed unanimously raised the rate by 25 basis points to 3.75–4.00%—the first increase since 2023—and signaled the possibility of another step by the end of the year. The regulator acknowledged that it cannot influence oil prices but intends to prevent the spread of inflation. The yield on 10-year U.S. bonds is around 5%. For the energy sector, this means an increase in capital costs: capital-intensive projects in renewables, networks, and LNG are under pressure, while oil companies with strong cash flow appear more resilient.
What to Watch for Investors and Energy Sector Participants on Friday
- The pace of recovery of the East-West pipeline and shipments from Yanbu.
- Tanker traffic through the Strait of Hormuz and the Bab el-Mandeb Strait.
- Confirmation of the energy truce by Moscow and Kyiv.
- Russia's decision on diesel exports after September 30.
- TTF dynamics, injection rates in European underground gas storage, and schedule for Norwegian maintenance.
- Weekly drilling activity statistics in the U.S. and diesel crack spreads.
The baseline scenario for the coming days is oil priced in the range of $100–110 per barrel with heightened sensitivity to news from the Middle East. Refined products and gas remain the most strained segments of the global energy market.