Oil Market: Weekly Gains Amid Risk Premium
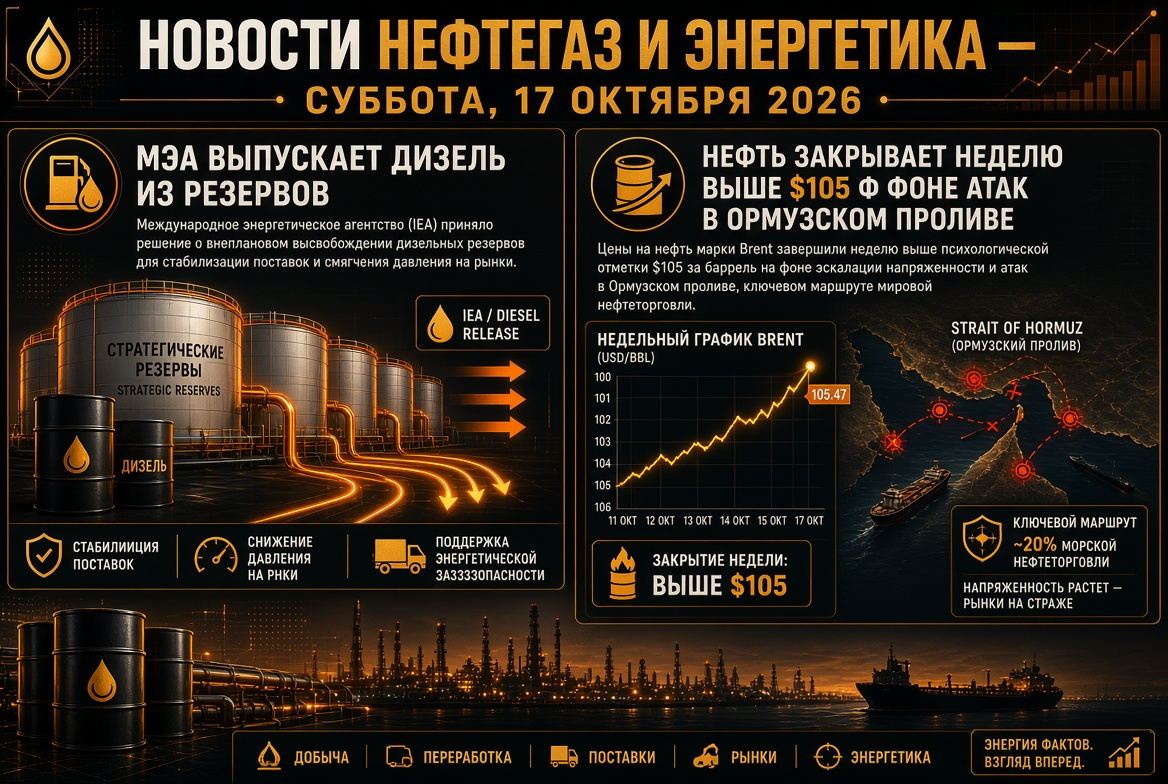
On Friday, oil prices saw a moderate decline, but the week for the oil market ends positively. December futures for Brent traded in a range of $105–105.5 per barrel, while WTI stood at approximately $97.
- Weekly dynamics: Brent rose by less than 1%, while WTI increased by around 6%.
- US Stockpiles: commercial oil inventories fell by 8.5 million barrels in the week ending October 9, contrary to expectations of slight growth. This marks the largest decline since the beginning of the war.
- Hurricane Factor: part of the production in the Gulf of Mexico was temporarily halted, providing support for the American grade.
- Brent-WTI Spread narrowed to approximately $8 per barrel after exceeding $9 earlier in the week.
Brent remains about 70% more expensive than a year ago. Analysts note that the market retains a significant geopolitical premium and that a full resolution requires an agreement between the US and Iran.
Strait of Hormuz: Oil Flows Recovering, but Unsteadily
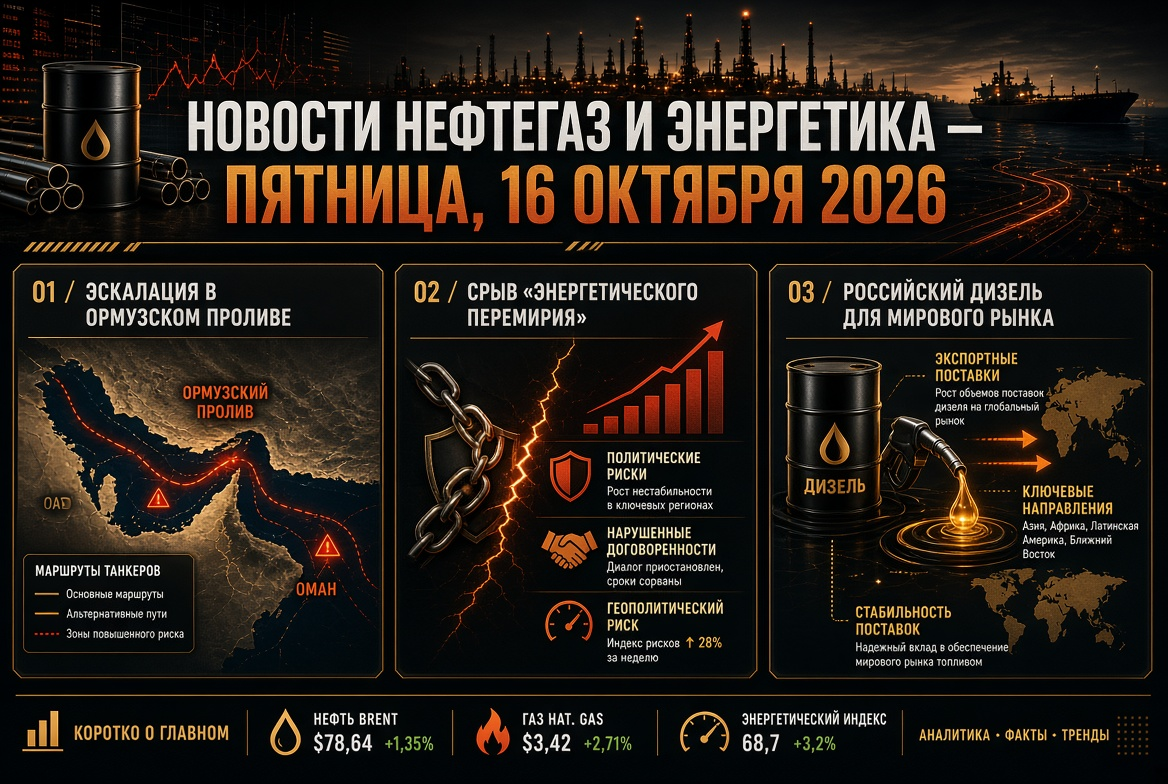
The situation in the Strait of Hormuz remains the key pricing factor for oil, LNG, and petroleum products.
- Crude Flows. In the seven days up to October 13, an average of about 11.6 million barrels per day passed through the strait, approximately 68% of the pre-war level of 17.15 million.
- Shipping. The number of transits for the week decreased to 131. Many container lines have rerouted to avoid the strait.
- Incidents. Following the sinking of the container ship GFS Pride, there were new reports of a fire on a tanker in the Gulf of Oman.
- Conflicting Signals. Tehran claims to have closed the strait, while US military command reports that over 19 million barrels of oil passed through escorted.
High prices make voyages commercially viable even amidst military risks: demand from Asian buyers encourages shipowners to continue transportation.
IEA and G7: Second Major Reserve Release This Year
The IEA has decided to put 100 million barrels back on the market as part of the March agreement, including over 20 million barrels of diesel fuel. This continues the G7 countries' agreement from October 2 to release reserves over four months, with priority for diesel shipments in the first 20 days.
- The diesel refining margin in Europe dropped by nearly 2% following the announcement.
- Several analysts believe that the reserves only partially ease tension in the middle distillate market.
- The US is considering relaxing sanctions on "shadow fleet" vessels to lower record freight rates.
Fuel Oil — A New Narrow Segment
In addition to diesel, the shortage of marine fuel is becoming more acute. According to Vitol, the conflict in the Middle East has reduced fuel oil supplies from the Persian Gulf by approximately 800,000 barrels per month, while strikes on Russian refineries have cut this by an additional 1 million tons per month. For bunkering companies and shipping, this means sustained high fuel prices.
OPEC+: Quotas on Hold, Production Below Targets
Seven key OPEC+ participants — Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman — have maintained their quotas for November unchanged.
- Target levels: around 10.5 million barrels per day for Saudi Arabia, 9.9 million for Russia, and 4.4 million for Iraq.
- The actual production of the core alliance in August was approximately 25 million barrels per day, about 5 million below pre-war levels.
- Approximately 2 million barrels per day of cuts remain in effect.
- An audit of production capacities will determine the baseline levels of production for 2027.
The next meeting of the alliance is scheduled for November 1. OPEC+'s influence on the physical oil market remains limited for now: logistics in the Persian Gulf play a decisive role.
Gas and LNG: Europe Enters Winter with Supply Shortages
The European gas market remains one of the most strained segments of the global energy landscape.
- Prices: TTF futures trade around €86 per MWh, which is approximately 2.6 times higher than a year ago.
- Storage: EU gas storage facilities are about 74% full against a five-year norm of about 89%. Brussels has lowered the target from 90% to 80%.
- Asia: the JKM index hovers around $26 per MMBtu, with Europe and Asia competing for every LNG cargo.
During the Russian Energy Week, the notion of a "golden age" for gas was discussed: it is no longer viewed solely as a transitional fuel. Notably, SOCAR announced plans to purchase gas from Gazprom — a signal of restructuring regional gas flows.
Coal: Expensive LNG Revives Demand in Asia
Newcastle thermal coal is trading around $150 per ton. The October high of $152.20 is the highest level since October 2024, with an annual increase exceeding 40%.
- High-quality thermal coal is approximately $20 per MMBtu cheaper than LNG in key Asian markets.
- Total coal imports by China, Japan, and South Korea in Q4 may increase by about 20 million tons.
- In Russia, industry estimates indicate that losses for coal companies may decrease by around 200 billion rubles by 2027.
Power Generation and Renewables: Betting on Reliability
The energy crisis is accelerating investments in both renewable energy and backup generation.
- In Europe, energy companies are combining solar stations with storage, reducing reliance on gas during peak hours.
- In Russia, Gazprom Energoholding plans new plants in Moscow with capacities of up to 480 MW, while distributed generation is discussed as a necessary measure.
- On October 29, the IEA will present the Renewables 2026 report with updated forecasts for renewables capacity additions.
Russia: Oil Product Market, Refineries, and Production
The domestic fuel market in Russia is showing short-term stabilization amid restrictions and the diesel deal with the US.
- Retail: the average price of gasoline is 78.68 rubles per liter, and diesel fuel is 86.67 rubles. Since the start of the year, gasoline has risen by 21.4%, and diesel by 13.5%.
- Exports: the ban on gasoline exports is effective until January 31, 2027, while restrictions on diesel exports have been lifted early.
- Diesel Deal: shipments to the US and global markets are 300,000 tons in October, 500,000 tons in November, and 1 million tons in December.
- Production: The Laya vozskoe field in the Nenets Autonomous Okrug has entered pilot production. The Ministry of Energy and the Ministry of Finance are recalibrating tax incentives for hard-to-extract reserves.
The primary risk for the refining sector is the state of refineries following the disruption of the "energy truce": the loading of plants is directly linked to export volumes of petroleum products.
What’s Important for Energy Sector Investors Next Week
- Strait of Hormuz: an increase in oil flows could reduce risk premiums; new attacks could push Brent back to $110.
- IEA Reserves: the pace of diesel's arrival in the market will determine the dynamics of crack spreads and refinery margins.
- Sanctions on "Shadow Fleet": an official decision from the US could lower freight rates.
- EIA Data on US oil inventories on October 21.
- Bank of Russia Meeting on October 23: inflation has accelerated to 7.2%, which is crucial for assessing the stocks of oil and gas companies.
- Political Calendar: OPEC+ meeting on November 1, and midterm elections in the US on November 3.
The week's conclusion: the global markets for oil, gas, coal, and petroleum products remain structurally deficient. The release of strategic reserves and new logistical schemes are mitigating price spikes, but they do not eliminate the main cause of tension — instability in supplies from the Persian Gulf. For participants in the energy market, priorities remain price risk hedging, supply diversification, and maintaining refining margins.