The week in global energy markets: oil, gas, coal and refined products ahead of the OPEC+ decision
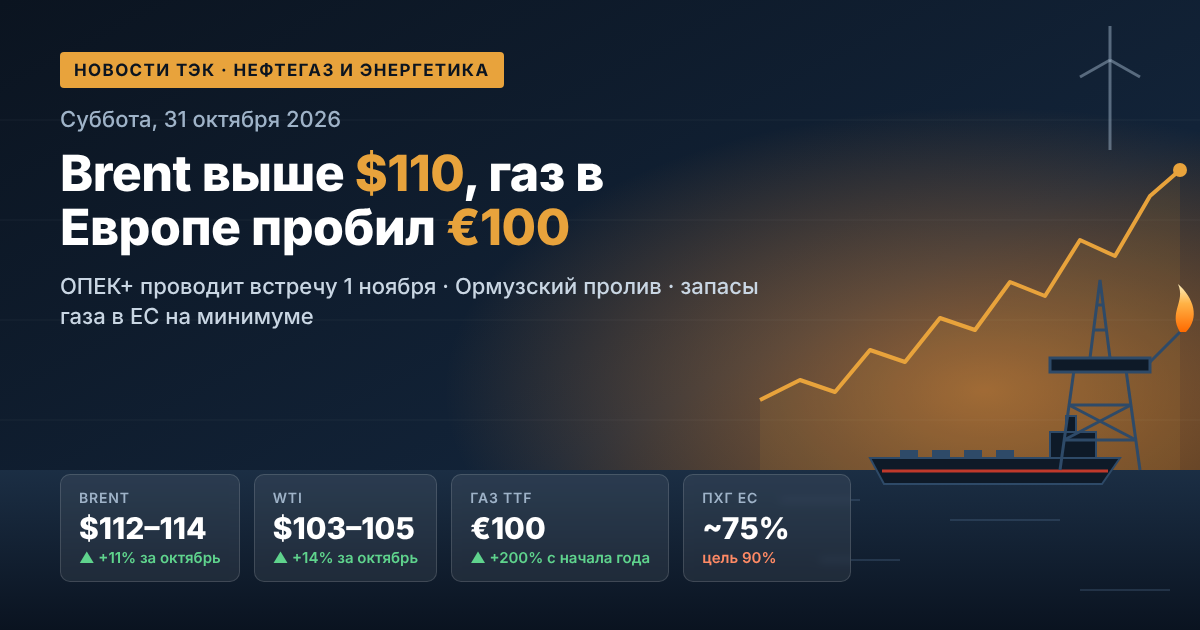
Global oil and gas markets are entering November at multi-year highs. In October, Brent crude rose by around 11% and WTI by 14%: both benchmarks have now gained for four consecutive months. On Friday, the December Brent futures contract, on its last day of trading, climbed to $118 a barrel for the first time since 30 April. The drivers were fresh Houthi attacks on Saudi Arabia's oil infrastructure, an attack on a tanker in the Strait of Hormuz, and expectations of a possible escalation in the US–Iran conflict following the US midterm elections. On Sunday, 1 November, seven key OPEC+ members are holding an online meeting on December quotas. European gas, meanwhile, is priced above $1,200 per thousand cubic metres for the first time since December 2022.
1. Oil market: Brent and WTI close October higher
For Brent crude, the past week was one of the most volatile since spring. On Thursday, prices slipped to $110–111 on reports of diplomatic contacts: the US side sent Tehran a letter proposing a resumption of talks. By Friday, the geopolitical risk premium had returned to prices.
- Brent (December contract): up to $118 a barrel intraday, a six-month high;
- Brent (January contract): around $113–114 a barrel, up 2.5% for the session;
- WTI: around $103–105 a barrel, a high since September;
- Brent–WTI spread: narrowed to around $9: US crude is catching up with European.
Analysts expect high oil prices to persist even after the conflict ends. Saxo Bank expects Brent to trade in a $70–90 range instead of the pre-war $60–70: the market will need to rebuild inventories, and the risk of hostilities resuming will not disappear.
2. Middle East: strikes on Ras Tanura, Abqaiq and Rabigh
The main source of tension for oil companies and traders is the escalation on the Arabian Peninsula. The Houthis claimed six attacks on targets in Saudi Arabia, including:
- the Ras Tanura refinery with a capacity of 550,000 barrels per day (the second attack in a week);
- the Rabigh refinery;
- a Saudi Aramco facility at Abqaiq;
- the East–West pipeline, through which the kingdom routes exports to the Red Sea bypassing the Strait of Hormuz. By early October, throughput along it had recovered to 5.8 million barrels per day.
Riyadh has not yet officially confirmed these strikes. Nevertheless, the market treats disruptions to Middle East oil supplies as a real risk. On Friday, the UK Maritime Trade Operations (UKMTO) also reported a tanker in the Strait of Hormuz damaged by explosive devices attached from a small craft.
3. OPEC+: the 1 November meeting and 2027 quotas
Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman are meeting on Sunday. According to sources within the alliance, the base case is to keep December quotas unchanged. This would be the third consecutive pause after six months of gradual output increases.
OPEC+ quotas for November 2026
- Saudi Arabia — 10.5 million barrels per day;
- Russia — 9.9 million barrels per day;
- Iraq — 4.4 million barrels per day;
- Kuwait — 2.7 million barrels per day;
- Kazakhstan — 1.6 million, Algeria — 1.0 million, Oman — 0.8 million barrels per day.
The decision is largely symbolic: actual production in the Persian Gulf is still well below quotas. For investors, the signals on 2027 policy matter more. The alliance is maintaining around 2 million barrels per day of cuts introduced in 2022 and has yet to complete its audit of members' production capacity, on which new baseline levels will be set. A full OPEC+ ministerial meeting is scheduled for 29 November.
4. Supply and demand balance: inventories are shrinking
According to IEA estimates, global oil demand will fall by 2.6 million barrels per day in 2026, to 102.4 million. Supply will drop even more sharply — by 5.8 million barrels per day. As a result, the market remains in deficit until the end of the year:
- by the end of September, global oil inventories were 509 million barrels below the level at the end of February;
- around 330 million barrels have already been released from IEA member countries' strategic reserves, with the remaining volumes to be released faster, diesel first;
- the middle distillates deficit is expected by the agency to persist into 2027.
OPEC has also cut its forecast for global demand growth in 2026 — to 400,000 barrels per day from an initial 1.4 million.
5. Asia: China returns to buying
China's oil imports in October are estimated to exceed 10 million barrels per day — the highest since March. Chinese refineries are receiving cargoes contracted in early August, when Brent was below $80. China's commercial inventories are estimated at around 1.19 billion barrels, and with imports rising, their drawdown may come to an end. For exporters, this supports demand. For Russian suppliers, the picture is more complicated: India is buying Middle East crude more actively, and exports from the Persian Gulf states recovered to around 75% of pre-war levels in September.
6. Russian oil and refined products: Urals discounts and the diesel export ban
October was a mixed month for Russia's oil and gas sector. Absolute Urals prices rose in line with Brent, but discounts widened. At the Novorossiysk port, the discount for Suezmax cargoes reached $28.85 a barrel — the highest since March — while freight rates hit all-time highs. In the domestic refined products market, the authorities continue to intervene directly:
- the ban on petrol exports for all market participants is in force until 31 January 2027;
- the ban on diesel exports for producers was due to expire on 31 October. According to industry data, it is to be extended to the end of 2026, with quota-based supplies maintained;
- following talks between the Russian and US presidents on 9 October, US sanctions on Russian diesel were suspended for six months, until 7 April 2027;
- the State Duma passed the 2027–2029 budget in its first reading, which sets a lower base oil price for calculating oil and gas revenues.
7. European gas market: TTF above €100/MWh
European gas has risen to its highest level in almost four years. The day-ahead price at the TTF hub reached around €104/MWh on Friday (about $1,204 per thousand cubic metres), with the December futures at around €103. According to GIE, as of 26 October EU underground gas storage was 74.9% full (80 billion cubic metres), well below last year's level. Europe is competing with Asian buyers for LNG cargoes, and Gazprom chief Alexey Miller has suggested peak prices could reach $2,500 per thousand cubic metres in a cold winter.
8. Coal and power: gas gets more expensive, coal comes back
Expensive LNG has revived coal demand in Asia. Newcastle thermal coal is trading at around $150 a tonne — near three-year highs and 45% more expensive than a year ago. On an energy-equivalent basis, coal is roughly 80% cheaper than LNG, so China, Japan and South Korea may increase imports by around 20 million tonnes in the fourth quarter. For generating companies, this means higher fuel and electricity costs; for coal exporters, a strong end to the year.
9. Renewables and the energy transition: the road to COP31
The renewable energy focus is on the COP31 climate conference, to be held in Antalya from 9 to 20 November. The Turkish and Australian presidency is promoting the "35 by 35" goal: raising the share of electricity in global final energy consumption to 35% by 2035. In November, the IEA will also present its Renewables 2026 and World Energy Outlook 2026 reports. The 2026 energy crisis has reinforced interest in energy security, electrification and energy storage.
What market participants should watch this week
- 1 November — the OPEC+ decision on December output and signals on 2027 quotas;
- 3 November — the US midterm elections: the market fears a resumption of strikes on Iran afterwards;
- shipping in the Strait of Hormuz and attacks on Saudi refineries and pipelines;
- gas withdrawals from European storage and TTF dynamics as the cold weather sets in;
- the Russian government's final decision on diesel exports.
In early November, commodity markets are being driven above all by geopolitics and inventory shortages. For investors and oil and fuel companies, this means high price volatility across oil, gas, coal and refined products at least until the end of the year.