Oil Market: Brent Balances Around $100
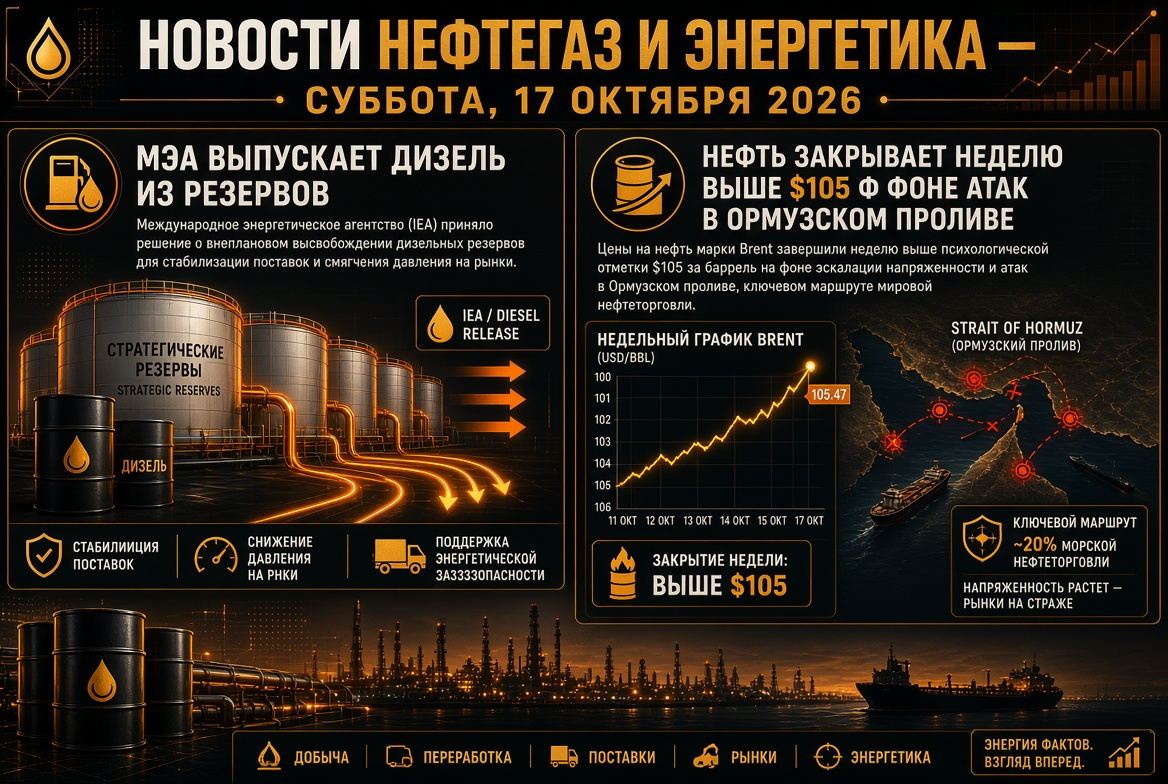
Oil prices are closing the week with high volatility. On Friday, Brent fell about 2.5% to just below $100 per barrel, while WTI dropped nearly 4%, approaching $89. The day before, Brent was holding above $102. Despite the correction, oil remains approximately 1.5 times more expensive than a year ago.
Prices are influenced by conflicting factors:
- Reserves: The European Commission is discussing with IEA participants the timing of a new coordinated release of strategic reserves.
- Export Recovery: Non-Iranian oil shipments through the Strait of Hormuz returned to pre-war levels of 13.5 million barrels per day at the end of September, according to tracking data, thanks to escorting of vessels.
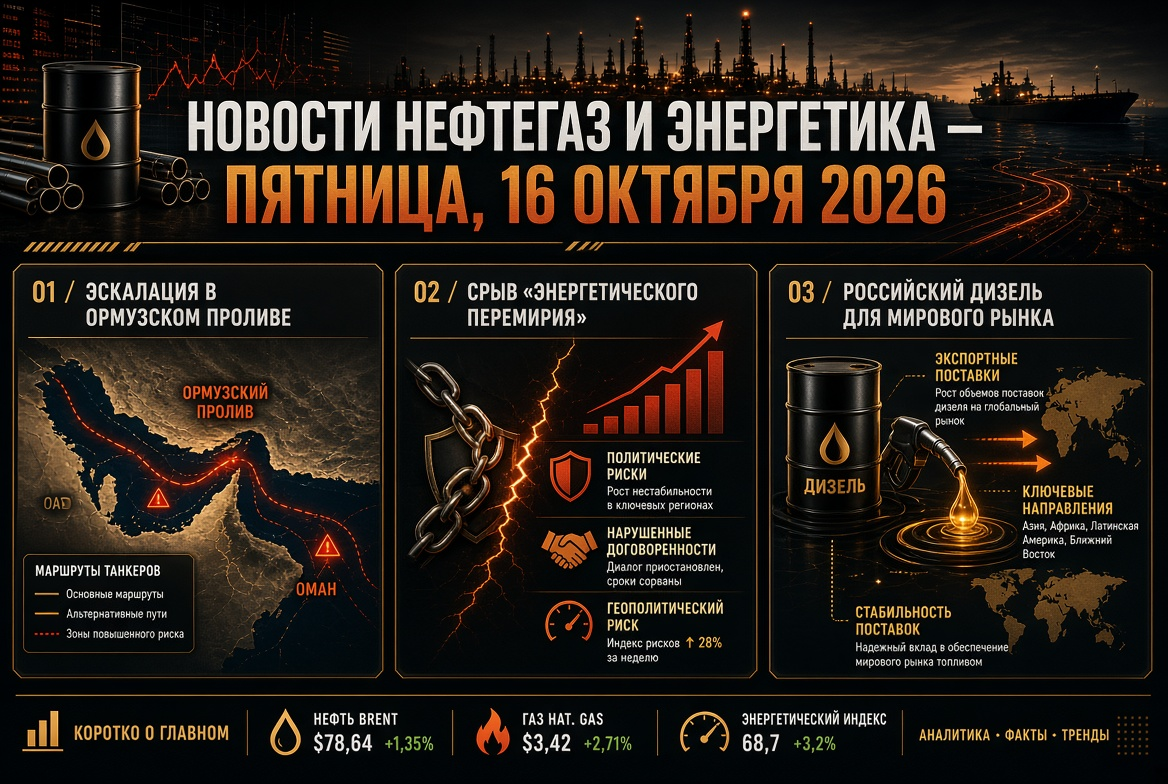
- Security Risks: This week, three tankers in the Strait were hit by unidentified projectiles, and negotiations between the US and Iran remain stalled.
- Stocks: According to the US Department of Energy, global oil reserves have decreased by approximately 400 million barrels since the beginning of the year.
OPEC+: Meeting on October 4 and the 2027 Quota Question
On Sunday, October 4, seven key OPEC+ members—Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria, and Oman—will hold their monthly meeting. According to sources, the quotas for November will remain unchanged. Formal target levels have long diverged from reality: the actual output of the alliance is about 5 million barrels per day lower than pre-war levels, as Gulf countries are unable to fully export crude oil.
The main intrigue shifts to 2027: the alliance is completing an audit of production capacities, which will determine new baseline production levels. For oil companies and investors, this is a question of long-term market share distribution.
Petroleum Products and Refineries: Diesel Becomes the Main Shortage
The petroleum product market is currently tighter than the crude oil market. Diesel prices are setting new records in many countries, exceeding $6 per gallon in the US. In just a few days, supply has diminished across multiple fronts:
- China has suspended exports of gasoline, diesel, and jet fuel for October, except for shipments to Hong Kong and Macau. Domestic fuel inventories have dropped to multi-year lows, with a decision on resumption expected after the holidays ending on October 7.
- Russia has extended its ban on diesel exports for producers until October 31.
- India: An explosion at a major export-oriented refinery has led to the cancellation of some tenders.
- US: The US is considering a ban on diesel exports if Germany and France do not release fuel from reserves. American refineries are operating at about 97% capacity, and Washington acknowledges that a ban could drive up gasoline prices.
Germany and France account for about 35% of the EU's strategic diesel reserves, estimated at 39 million tons—over two months of consumption. Analysts estimate that an American ban would hit Latin America the hardest. The UN warns that global fuel subsidies could exceed $1 trillion.
Gas and LNG: Europe Enters Winter with Supply Deficit
The European gas market remains one of the most vulnerable segments of energy. Prices at the TTF hub hover around €73 per MWh, which is about double last year's levels. EU underground storage is filled to only 71.5%—about 20 percentage points below seasonal norms.
- Germany has instructed SEFE to inject an additional 8 TWh of gas into storage.
- The EU is considering a one-year postponement of methane regulations for imported gas to avoid restricting LNG supplies.
- The head of Japan's JERA has warned that LNG prices have not yet exhausted their potential for growth.
- LNG imports to China are declining for the second consecutive month, and Pakistan is exploring direct purchases for power generation.
Long-term investments in the sector are accelerating: ConocoPhillips has signed a 20-year LNG contract with Venture Global, and Shell has approved the second phase of LNG Canada, which will double the export capacity of the project.
Coal: Prices in China at a Three-Year High
Coal is once again serving as a fallback resource for energy systems in Asia. The benchmark price of thermal coal at the Qinhuangdao port has increased for 11 consecutive weeks, reaching 986 yuan (approximately $147) per ton—the highest in three years. Since mid-July, prices have risen 24% due to a decline in domestic production following safety inspections and a reduction in imports from Indonesia by about a quarter.
Coal accounts for nearly half of electricity generation in China, and authorities have urged mines to maintain stable production levels. In India, the IEA expects coal demand to grow by 4.2% this year, reaching 1.353 billion tons.
Electricity, RE and Nuclear Energy
Global demand for electricity is growing at its fastest pace in 15 years—driven by data centers, artificial intelligence, and electrification. Networks and generation are struggling to keep pace with consumption, particularly evident in emerging markets.
- India: Electricity shortages in September reached 560 million kWh—the highest since August 2023. Nearly 40% of coal-fired stations are operating at critically low fuel levels. Renewable energy output increased by 25.1%, but its share in generation fell to 17%.
- Nuclear Energy: Amazon has signed a 20-year agreement for nuclear electricity supply with Constellation, and uranium prices have reached historic highs.
- Europe: Three EU countries are advocating for a new renewable energy target by 2040.
The energy crisis strengthens the case for renewable energy, storage solutions, and nuclear generation as instruments of energy security, rather than solely climate policy.
Asia: India and China Restructure Imports
India is increasing purchases of Middle Eastern oil while reducing imports from Russia; its refiners are seeking tankers for routes through Hormuz. New Delhi emphasizes that high prices are due to chaos in shipping, not a shortage of raw materials. The rise in oil prices has already led to an outflow of $3.2 billion in foreign investments from Indian markets. Analysts have also reduced China's oil import forecast for the fourth quarter by 400,000 barrels per day. Taiwan has allocated $13 billion to protect consumers from high energy costs.
Russia: Export Restrictions and Domestic Fuel Market
The Russian petroleum market remains under strict regulation. In addition to the ban on diesel exports for producers until the end of October, there is a ban on gasoline exports until the end of January and restrictions on jet fuel exports until November. Authorities explain these measures by the high demand during the harvest period and the need to replenish stocks after drone attacks on refineries. Retail gasoline prices have increased by approximately 21% since the beginning of the year, and the antimonopoly service is investigating dozens of independent gas station networks.
What to Watch for Investors and Energy Market Participants
- October 4: OPEC+ decision on November quotas and signals regarding parameters for 2027.
- October 7: End of holidays in China and potential resumption of fuel exports.
- IEA and EU Reserves: Volume and timing of oil and diesel releases.
- US Decision on the diesel export ban and the refining margins response.
- Strait of Hormuz: Shipping security and the progress of US-Iran negotiations.
- Weather in Europe: Early cold weather with storage at 71.5% could sharply raise gas and electricity prices.
The baseline scenario for the coming days indicates continued high volatility: oil reacts to news about reserves and the Hormuz Strait, while petroleum products, gas, and coal remain structurally deficient. For oil and fuel companies, this means high refining margins, while for consumers and importers, it indicates continued price pressure.