Oil, gas and energy news for 31 October 2026 shows the global fuel and energy complex entering winter with very high prices. Brent crude is holding above US$110 a barrel, and attacks on tankers in the Strait of Hormuz continue. European gas has risen to €100 per MWh for the first time since 2022, and OPEC+ is preparing to discuss December quotas. Below are the main events in the commodity and energy market over the week and what they mean for investors, oil and fuel companies.
Key figures of the week in fuel and energy markets
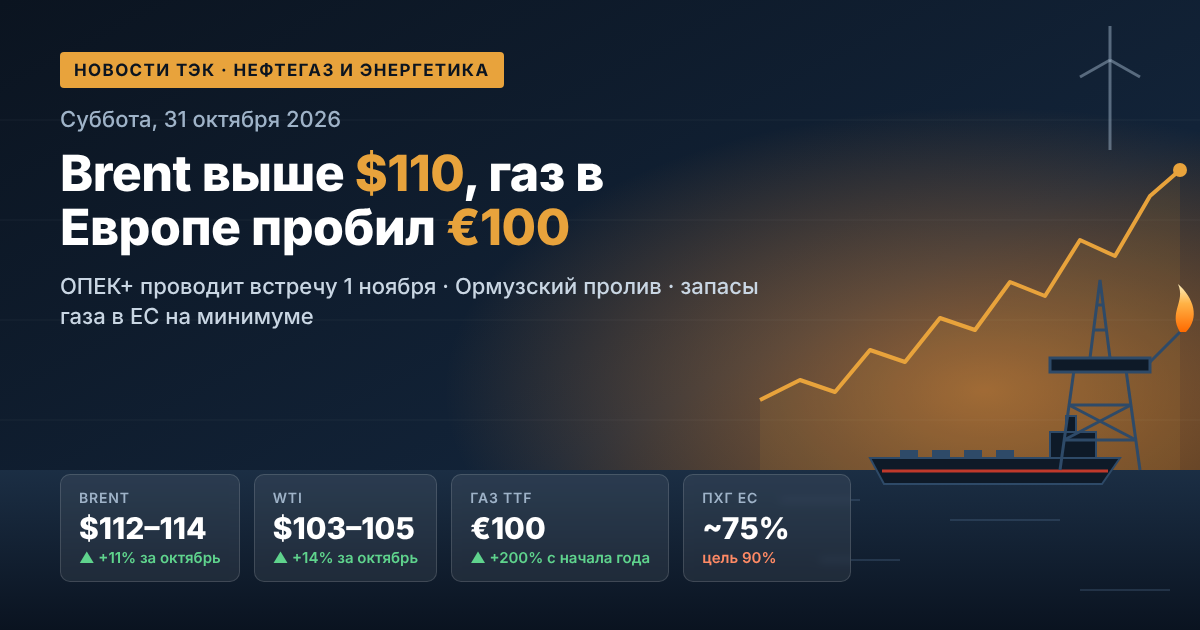
- Brent crude (January futures): US$112–114 a barrel, rising to US$114.06 during Friday trading.
- WTI: around US$103–105 a barrel, with the spread to Brent narrowing to about US$9.
- October gains: Brent rose about 11%, WTI about 14%.
- TTF gas: around €100 per MWh, up more than 200% since the start of the year.
- EU gas storage: around 75%, against the usual benchmark of 90% by 1 November.
Oil market: geopolitical premium is rising again
On Thursday evening oil prices fell as the market reacted to fresh attempts to resolve the Middle East conflict diplomatically, with Brent dropping to around US$110. On Friday morning prices recovered the losses after reports of an attack on a tanker in the Strait of Hormuz. Investors saw that the threat to crude supply has not gone away.
The situation is contradictory. Oil exports from the Middle East have recovered to almost 80% of pre-war levels, and flows through the Strait of Hormuz have risen to 10.9 million barrels a day. Yet more than 28 attacks on vessels have been recorded in the strait and adjacent waters since the start of October. So there is more physical crude on the market, but the risk premium remains high.
What will influence oil in the coming weeks
- Progress in indirect negotiations between the US and Iran, and contacts between Riyadh and Tehran.
- Safety of shipping in the Strait of Hormuz and the cost of insuring tankers.
- Parliamentary elections in Israel and the US elections, which could increase volatility.
- Revisions to demand forecasts: OPEC has cut its estimate for global oil consumption growth in 2026 to 0.4 million b/d from 1.4 million b/d previously.
OPEC+: 1 November meeting and preparation of 2027 quotas
On Sunday, 1 November, seven key OPEC+ countries will hold an online meeting: Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman. The market expects December production targets to remain unchanged. Current benchmarks:
- Saudi Arabia — 10.5 million b/d;
- Russia — 9.9 million b/d;
- Iraq — 4.4 million b/d;
- Kuwait — 2.7 million b/d;
- Kazakhstan — 1.6 million b/d;
- Algeria — 1.0 million b/d, Oman — 0.8 million b/d.
In September the alliance fully returned 1.65 million b/d of voluntary 2023 cuts to the market, but in practice most of those volumes never materialised. In August the seven countries produced around 25 million b/d — roughly 5 million b/d less than before the war. Around 2 million b/d of 2022 cuts remain in force until the end of the year. The main topic for investors is the assessment of members' production capacity: base levels and 2027 quotas depend on it. A full ministerial meeting is scheduled for 29 November.
Gas and LNG: Europe enters winter with minimal stocks
Europe's gas market is currently the main pressure point in global energy. On 28 October the TTF futures exceeded €100 per MWh for the first time since 2022, and by Friday the price had settled around that level. Key reasons:
- LNG shortfall: Qatar is operating under force majeure until the end of November, and supplies from the Persian Gulf region are partly blocked.
- Low storage levels: around 75% in the EU and around 61% in Germany. For this time of year this is a record low.
- Competition with Asia for LNG cargoes: in mid-October European regasification terminals were loaded at an average of only 37%.
According to the European regulator ACER, the war has already increased the EU's gas import costs by €18–33 billion. ENTSOG warns that if the LNG deficit persists, storage could fall below 30% by the end of winter. The spread between European TTF and US Henry Hub (around US$3 per MMBtu) has widened to about US$27 per MMBtu. This makes US LNG exports highly profitable.
Power and renewables: the crisis accelerates the energy transition
Expensive gas immediately makes electricity more expensive too: in the wholesale market, peak-hour prices are usually set by gas-fired power plants. In several regions governments have already introduced emergency energy-saving measures.
At the same time, the crisis is spurring the development of renewable energy. According to IEA forecasts, in 2026 renewables will overtake coal for the first time and become the world's largest source of electricity. Solar output will grow by around 600 TWh, and solar generation will overtake wind to become the second-largest renewable source after hydropower. For energy importers in Europe and Asia, domestic renewable generation is increasingly a matter of energy security.
Coal: demand supported by expensive gas
With gas at around €100 per MWh, power companies in Europe and Asia often choose coal instead of gas. This supports demand for thermal coal, especially from Asian importers competing with Europe for LNG. On the other hand, Black Sea routes remain risky for shipping, which complicates logistics for some suppliers. As a result, the coal market remains dependent on the gas situation: while gas is expensive, coal has steady demand.
Russian oil: revenues above budget benchmarks
For the Russian oil and gas sector, high world prices mean additional revenue. In the first three weeks of October companies received an average of around RUB 8,700 (US$103.4) per barrel for Urals — 11% more than in September and around 60% above the level assumed in the budget (the budget benchmark is US$59 a barrel).
But costs are rising too:
- the Urals discount to Dated Brent at Baltic ports has widened to around US$21 a barrel because of competition with Middle Eastern oil in the Indian market;
- freight for Suezmax and Aframax tankers from Baltic and Black Sea ports to India has risen to a record US$27–32 a barrel;
- shipping in the Black Sea region has become noticeably more dangerous, and insuring vessels there is more expensive.
Refined products and refineries: Russia's fuel market under manual control
The domestic refined products market in Russia remains in regulators' focus. From 1 August 2026 to 31 January 2027 exports of petrol, diesel and bunker fuel are banned. On the St Petersburg exchange, price increases are capped at 0.01% a day. On 22 October the AI-95 petrol index for the European part of the country fell 13.4% to RUB 69,700 per tonne.
Measures regulators are discussing
- Restricting access to exchange trading for participants who place bids at inflated prices.
- Tightening control over independent traders and automated purchases on the exchange.
- Developing long-term mechanisms to stabilise wholesale prices together with the FAS and the Ministry of Energy.
At the pump, the average litre of petrol cost around RUB 78.7 in mid-October, with AI-95 at almost RUB 81. For refineries and independent service stations, margins remain under pressure.
Outlook for investors and fuel and energy market participants
The week from 2 November could prove one of the most important for the global fuel and energy sector this year. What to watch:
- Outcomes of the OPEC+ meeting on 1 November and signals on 2027 quotas.
- Middle East negotiations: if a truce is reached, Brent could quickly lose up to US$10–15 of its geopolitical premium.
- Europe's weather in November: this will determine how quickly gas stocks are drawn down and how gas and electricity prices behave.
- Elections in the US and Israel, which could amplify swings in commodity markets.
Overall, oil, gas and electricity remain in a regime of deficit and high volatility. For producing and exporting companies this delivers windfall profits, while for importers, refiners and energy-intensive industry it means rising costs and risks.